Tag: Wealth Erosion

از دست رفتن تدریجی ثروت در طول نسل‌ها، با هر علتی

  • Wealth That Doesn’t Show Up in Financial Reports

    Wealth That Doesn’t Show Up in Financial Reports

    In years of crisis, intergenerational wealth transfer is more than moving assets. It answers one question: after all these years, does the heir still see the family’s wealth as their own?

    At the end of the film A Separation, Termeh must choose between her father and her mother. We see her in a home where three generations live under one roof: a grandfather who belongs to the first generation and can no longer move on his own, a middle generation torn between staying and leaving, and a third generation that has to choose. The film ends before we hear Termeh’s answer. The same scene plays out in families that own a business: the first generation built, the second hesitates between staying and leaving, and the next generation, without realizing it, is building a world of its own.

    Crises slowly open distances between generations: a distance of geography, a distance of experience, and a distance of language.

    This Genar article examines all three distances and offers ways to close them. At the end, you will find a quiz with a few questions you can raise at the family dinner table this week.

    What Is a Family’s Real Wealth?

    When people talk about family wealth, they usually mean financial statements and assets such as property, shares, and cash. But James Hughes (Family Wealth: Keeping It in the Family, Bloomberg Press, 2004), who has worked with multigenerational wealthy families for three decades, defines it differently. In his view, a family’s real wealth is the human, intellectual, and social capital of its members. Financial capital is not the goal here; it is a tool for growing those three forms of capital. This definition matters especially for wealthy Iranian families who have lived under the pressure of crisis in recent years, because it shows that the main danger does not always lie in the market.

    The Family’s Three Forms of Capital: Human, Intellectual and Social

    Social capital is the family’s network of relationships: the people who have worked with the family for years, the trust of a market and an industry that took years to earn, and a name, or more precisely the good reputation, that opens every door. No one builds this capital overnight, and no one inherits it from a distance.

    Intellectual capital is the knowledge and judgment that preserve and grow wealth: knowing where the wealth came from, the ability to make decisions under pressure and a horizon that sees ten years ahead. This is what turns an heir from an “owner” into a “steward.”

    Human capital is the family members’ ability to stay together: trust, dialogue between generations, and each person’s readiness for the responsibility entrusted to them. The other two forms of capital stand on this foundation.

    The important point is that none of these three forms of capital appears in the financial statements. A family can be financially healthy and, at the same time, be losing all three.

    How Do Crises Create Gaps?

    Crises are usually measured in the language of assets: a falling rial, market volatility, sanctions. But their more hidden effect changes the heir’s relationship with wealth. Migration, chronic inflation, and changing lifestyles pull the new generation away from the family’s wealth, and each distance erodes one of the three forms of capital.
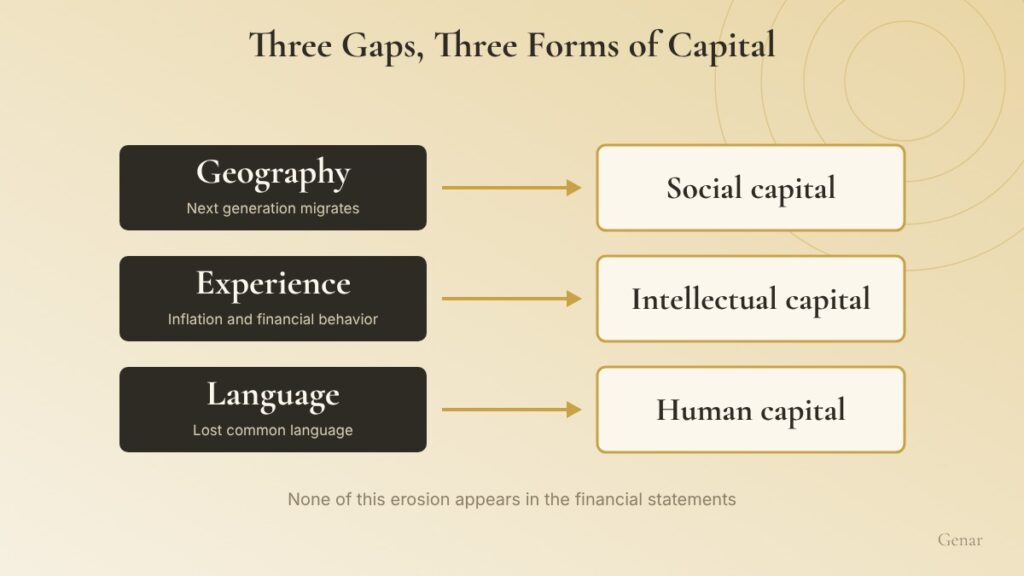
    Diagram of three rows: geography (migration of the next generation) leads to social capital, experience (inflation and financial behavior) to intellectual capital, and language (a language gap) to human capital, on a cream-to-gold gradient background
    Each distance erodes one of the family’s three forms of capital, and no financial statement records it.

    This erosion is slow; it does not show up in any financial report or get recorded in any month of the year. Yet trust has worn thin, or the heir no longer knows where the wealth came from. That is why preparing heirs must begin before financial warning signs appear and must be part of a family financial culture to which every generation contributes.

    Geography: Heirs’ Migration and the Erosion of Social Capital

    The migration of heirs is the first and most visible gap in social capital, the relationships and trust on which family wealth stands. Families usually prepare for someone’s absence before that person even leaves. Decisions start being made without them, and the person gradually adapts to this as well.

    Migration Among Entrepreneurs and Senior Managers

    If you think this is a story about young people with nothing to lose, the numbers say otherwise. In the survey of the Iran Migration Yearbook 1401 (2022–23), the desire to emigrate among entrepreneurs and senior managers was higher than in most groups, reaching about 70 percent. Those who have the most capital to manage think most about leaving.

    Leaving is usually one-way, too. In the same yearbook, 62 percent of Iranian emigrants had firmly decided not to return, and only 14 percent were certain they would go back. These figures predate the war, the heavy sanctions and the blockade.

    For an ordinary family, migration means leaving. For a family whose wealth is rooted in this soil, it means being split in two. But what suffers most are the relationships built over decades: the market’s trust and the credibility that opens the way to every deal. None of it fits in a suitcase, and none of it can be inherited from a distance.

    A Distant Heir or an Absent Heir?

    An heir can become absent without migrating. Someone who receives the reports and only skims them will one day own something they never had a role in running. This absence happens without a single flight.

    On the other hand, a member of the next generation who lives outside Iran can also be the family’s greatest asset: someone who has tested themselves and their skills outside the shadow of the family name and sees beyond the usual routine of the family business. The experience of one generation of the Grant family illustrates this well. The difference between these two heirs is not geography. It is the answer to one question: can this heir be trusted with a real decision and the responsibility that comes with it?

    Responsibility Instead of Video Calls

    When an heir to a family business emigrates, the usual response is to keep minimal contact: a weekly call, sending reports and passing on major news. This contact is valuable, but it does not close the gap, because the heir is only a listener. They know what happened, but nothing depended on their decision. People become attached to things whose outcomes depend on them, not to things they are merely informed about.

    Social capital works the same way. The family’s network (partners, suppliers, bankers and long-serving managers) does not survive on names alone; its continuity depends on decisions and accountability.

    If this network knows the heir only as “So-and-so’s son or daughter who lives abroad,” it sees them only as a name from the past. If it sees them as someone who has made a decision on a matter and taken responsibility for it, it sees a person it can work with in the future.

    What Makes Responsibility Real?

    Responsibility that exists only on paper is empty, and the heir quickly realizes it. For responsibility to be real, four conditions are needed:

    • Real decision-making: The heir does not give an opinion; they make the decision. If the elders always have the final word, the heir realizes their opinion was a formality.
    • Tangible results: The decision must produce a result that can be measured, whether it turns out good or bad. Responsibility that is never evaluated is practice, not responsibility.
    • A defined domain: The area that belongs to the heir must have clear boundaries. “Keep an eye on everything” gives no one responsibility, but “This part is yours” gives a person practical responsibility.
    • A regular schedule: Reviews at fixed intervals, for example, at the end of each quarter. Scattered decisions do not build a relationship; they create an irregular rhythm.

    Inflation, the Young Generation’s Experience and the Erosion of Intellectual Capital

    The second gap is not created by geography; it comes from experience. Two generations can sit in the same house and eat together, yet each has lived through the crises differently. This difference stems directly from intellectual capital: from how the heir sees wealth, what horizon they set for it, and what they rely on at the moment of decision.

    Experience Teaches; It Does Not Preach

    Most families begin preparing heirs with talk: about thrift, honesty, the hardship of building. But an heir learns less from what they hear than from what they live through.

    In A Separation, Termeh tips the gas station attendant, and Nader asks her to get the money back. Reluctantly, Termeh gets out of the car, argues with the man, and takes the money back, and Nader smiles and tells her to keep it. Her father gave her no lesson about right and wrong; she learned it with real money, a real person, and a little real fear. The film also shows the bitter side of this experience: Termeh, who learned honesty from her father’s words, lies to the judge at the end to protect him, because she learned concealment from his actions.

    This is not merely an observation about parenting. Ulrike Malmendier and Stefan Nagel, two leading economists, showed in “Learning from Inflation Experiences” (Quarterly Journal of Economics, 2016) that people give too much weight to the inflation they have experienced themselves and build their financial decisions on it. The effect is stronger among younger people, because recent experience makes up a larger share of their lives. Put simply, each generation understands money through the crisis it has seen, not through what it has been told.

    A Generation That Has Seen Only Inflation

    Imagine someone who is 25 today and has seen nothing but inflation. Since the Iranian year 1398 (2019–20), annual inflation has not fallen below 30 percent in a single year: from 34.8 percent that year to 45.8 percent in 1401 (2022–23), and in August 2026, point-to-point inflation reached 89 percent. Their entire adult life has taught one lesson: money does not last, and it should be turned into another asset quickly.

    An ISPA survey in Mehr 1402 (fall 2023) showed the same pattern across Iranian society. People over 50 preferred bank deposits more than others, those aged 30 to 49 favored land and housing, and young people leaned toward gold and coins. Three generations, three logics for the same money, and each logic comes from crises that generation lived through firsthand.

    For most families, this is only a question of preserving asset value. But in a family that built its wealth, a larger issue weighs heavily: what is at risk is intellectual capital, that is, judgment, horizon, and the ability to see ten years ahead.

    An heir who has seen only inflation may be right to prefer trading over building. Under these conditions, if they see the family’s wealth as something to be traded rather than something that was built, the long-term view that preserves wealth slowly fades.

    The Founder’s Behavior in Crisis: A Lesson Plan for the Heir

    Here we must look at the other side of the issue: in these years, what has the founder done in the face of crisis? If the heir has watched the elders move capital into gold and foreign currency at every piece of bad news, that is where today’s lesson came from, not from advice at the dinner table. But if they have seen part of the profits reinvested in the business during the hardest years, the lesson they learned will be entirely different.

    Neither behavior is necessarily wrong; avoiding risk in a crisis is sometimes the wisest choice. The point is that the heir sees the behavior but does not understand the logic behind it unless someone explains it. So the founder’s behavior in crisis needs to become more deliberate, and the reasoning behind it needs to be shared with the heir.

    How Can We Give the Heir Real Decision-Making Experience?

    Building cannot be taught through advice alone; its experience can only be passed on, as in the gas station scene in A Separation. For families that own a business, this means a small but real investment decision with four features:

    • Real money: The amount can be small, but it must be real money, not a simulation. When the heir knows a mistake has a cost, they think differently.
    • A long horizon: The decision’s outcome should unfold over years, not weeks. The goal is for an heir who has made only short-term decisions to also experience the fruits of patience.
    • Shared review of results: Every few months, the older and younger generations should review the outcomes of decisions and the reasons behind them.
    • Reviewing earlier generations’ mistakes: When the founder talks about their own wrong decisions, the heir understands that making mistakes is part of building.

    The Lost Common Language and the Erosion of Human Capital

    The third gap is the quietest of all. In many families, two generations live side by side for years without understanding each other, and this erodes the family’s human capital: the gradual fading of trust, dialogue, and readiness to take on responsibility.

    In A Separation, Termeh is doing her Persian homework. The teacher has included an Arabic word in the list, and Nader insists that his daughter write its Persian equivalent, even if it costs her marks. The daughter is caught between her teacher and her father. Much the same happens at the dinner tables of business-owning families.

    The 70 Percent Rule: Fact or Myth?

    You have probably heard that 70 percent of fortunes are lost by the second generation. The number is repeated so often that few people have asked where it comes from.

    Researchers such as James Grubman (International Family Offices Journal, 2022) traced its origin and arrived at a study by John Ward (Keeping the Family Business Healthy, Jossey-Bass, 1987) that examined 200 family-owned manufacturing businesses in one U.S. state. But 70 percent did not show lost wealth either; it showed only that ownership of the business had not stayed in the family.

    So the number can be set aside, but the problem remains. The question is not what percentage fail; it is where failure begins and why.

    Wealth Is Lost at the Dinner Table

    The researchers who made the number famous also report a more important finding. Williams and Preisser (Preparing Heirs, Robert Reed Publishers, 2003) examined why transitions failed, although the raw data behind their research was never published. In 60 percent of cases, communication and trust within the family had broken down, and in 25 percent, heirs had not been prepared to take on responsibility. In other words, most fortunes are not lost in the market; their undoing is decided at the dinner table.

    The picture is the same in our neighborhood. In 2024, PricewaterhouseCoopers (PwC), one of the world’s four largest audit and advisory firms, surveyed the next generation of Dubai’s family businesses (NextGen Survey, Dubai edition). Half of them said one of the hardest parts of succession is that the current generation cannot or will not step back. Only 39 percent were sure their family had a succession plan. So in most families, succession in the family business is still not a plan; it is a conversation that keeps being postponed.

    A Values Gap or a Language Gap?

    This situation is usually called a values gap or a generation gap in business-owning families. But much of it is, at heart, a language gap.

    The founder built the business in a time of scarcity and relied on people; a contract was simply a handshake. The heir grew up with sanctions on one side and the internet on the other, and relies on data. Both want the business to endure; they simply talk about it in two different languages, and each assumes the other thinks the wrong way. Trust slowly declines, and with it, the readiness to take on responsibility.

    Reverse Mentoring: When Both Generations Are Teachers

    This problem has an old solution. In 1999, Jack Welch asked young employees at General Electric to teach senior executives how to use the internet. The practice later became known as “reverse mentoring,” and researchers such as Murphy (“Reverse Mentoring at Work,” Human Resource Management, 2012) studied its effect on learning across generations.

    Learning can be two-way in families too. The new generation teaches something real, from new tools to artificial intelligence and data analysis, that adds something new to the business. The older generation teaches negotiation, reading people, and making decisions under pressure, backed by more than 40 years of experience, not just a few books.

    For this relationship to work in practice, it needs a few features:

    • It must be real.
    • It must be regular.
    • The learning side must genuinely ask questions.
    • The results must be put to use.

    When both generations teach each other, neither remains a stranger to the other, and the questions that were always postponed (such as succession and handing over responsibility) begin to feel more like real, comfortable conversations.

    Three Gaps, One Chain

    These three gaps do not work in isolation. Each deepens the others, which is why the erosion of capital is often noticed late.
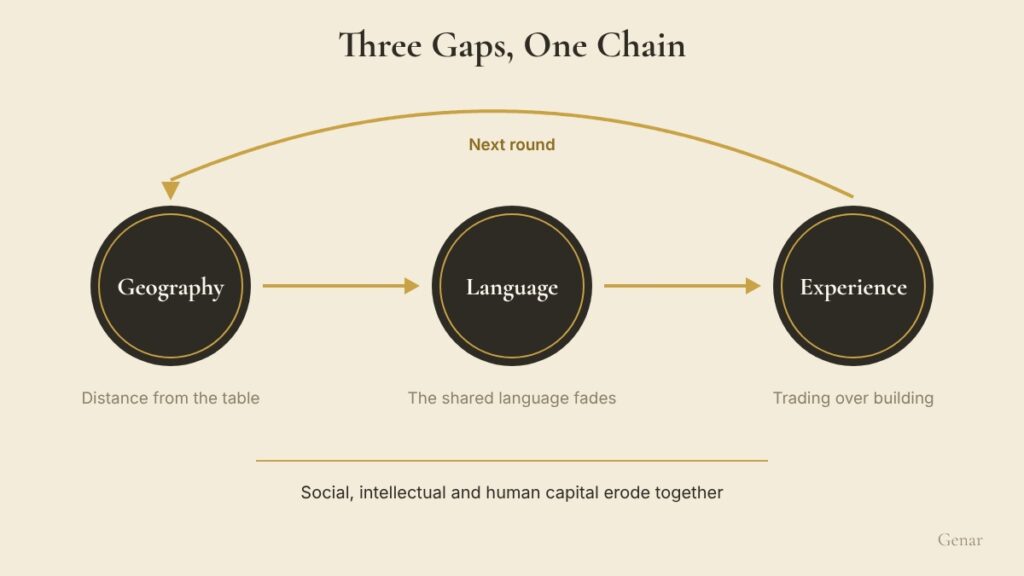
    Diagram of three circles linked by arrows: geography, language and experience, with a return arrow from the last to the first marking the next round
    The gaps do not work in isolation: distance fades the shared language, a lost language pulls the heir toward transactions, and the next round begins from there.

    Why Do These Three Forms of Erosion Happen Together?

    The chain can start from any link, but it usually unfolds like this: an heir who has moved away gradually understands less of the previous generation’s language. They are no longer at the table and do not see discussions and decisions up close. An heir who does not understand the language takes refuge in what is familiar: numbers and transactions. They see wealth as something to move and cash out, not something to keep. An heir who knows only transactions sees no reason to continue the business, and if profit is all that matters, it can be found anywhere.

    This is where the next round begins: the next generation drifts further away, the previous generation’s language becomes stranger and relationships fade. Social, intellectual, and human capital erode together, even while the financial statements still look good. That apparent health is exactly why no one hears the alarm.

    The Family Compact

    James E. Hughes Jr. says that to preserve its wealth, a family needs a shared compact: a clear agreement on why its members stay together, what the wealth is for, and what responsibility each person has toward it. More importantly, this compact is not inherited. Each generation must accept it anew. A compact made by the previous generation is only a memory until the next generation embraces it.

    Crises are the moments when such a compact is either renewed or abandoned. A family whose members sit together in the hardest years and ask, “Why are we still together?” renews its compact. A family that simply waits for things to improve has abandoned its compact, and nothing seems to happen until the day the heir says there is no place left for them. The next section is a quiz that shows where your family stands on this path right now.

    The Dinner Table Quiz: Where Your Family’s Heirs Stand

    Ask these nine questions at the family table this week. Answer each one for a specific heir, and if you have several heirs, repeat the quiz for each of them separately. Score each question: zero (no), one (partly), or two (yes).

    Social Capital (First Gap)

    1. Has the heir made at least one real decision about the family’s assets or business in the past six months?
    2. Do key people in the family’s network, such as partners and suppliers, know the heir by name?
    3. Does the heir have a reason other than emotion to stay involved with the family’s wealth?

    Intellectual Capital (Second Gap)

    1. Can the heir explain, in their own words, where the family’s wealth came from?
    2. Have they ever made a decision whose outcome took more than a year to unfold?
    3. In recent crises, has what they saw in the elders’ behavior been more building than fleeing?

    Human Capital (Third Gap)

    1. When did the older generation last learn something from them? (Within the past six months: 2; within the past year: 1; longer ago or never: 0)
    2. Has succession actually been discussed, rather than remaining in one person’s mind?
    • If the main decision-maker were unable to make decisions, would anyone know what to do?

    Scoring and Interpretation

    Add up the scores (maximum 18):

    • Below 6: The gaps are making decisions for you. Start preparing your heirs now.
    • 6 to 12: The gaps exist, but they are still in your hands. A little deliberate attention is enough.
    • Above 12: The family is consciously shaping its heir.

    Each section has a maximum of 6 points. The section with the lowest score shows which gap to start with. The total may look good while one form of capital is almost empty.

    One suggestion: have the older generation and the heir each complete the quiz separately, without seeing each other’s answers, and then compare the results. Where the scores differ is usually where the two generations do not understand each other’s language.

    From Stewardship as a Concept to Stewardship as an Experience

    In the final scene of A Separation, Termeh asks her parents to wait outside. The two of them stand apart in the courthouse corridor, behind a closed door, waiting for an answer they themselves spent years helping to shape. Termeh’s answer is the result of everything she saw and experienced in that home.

    Your family’s heir builds their answer from the same things: the city they live in, the crises they have seen and the words they heard, or did not hear, at the table.

    A gap is not closed with advice; it is closed with a shared decision that carries real cost and real responsibility. This is where stewardship turns from a concept into an experience. A steward is someone who sees wealth as something held in trust for the next generation and takes responsibility for preserving it. Such a view cannot be passed on through reading and listening alone. The heir must step into this role, make decisions, and stand by them. Genar’s Process was created to build exactly this experience.
  • Wealth Transfer Isn’t Just About Money

    Wealth Transfer Isn’t Just About Money

    Intergenerational wealth transfer is a sensitive subject for families, particularly wealthy ones. Yet they generally make the same mistake: they start with the money, turning first to investments, taxes, legal structures and wills. A question is asked far less often: before any money is lost, what else has already been lost?

    Ascending staircase chart of seven dark steps with gold edges and dots on a cream-to-gold gradient background
    What built the wealth does not pass to the next generation by itself. That is what is lost before the money.

    Behind every great fortune lie years of decisions, risk, and experience. The problem is that what enabled one generation to build wealth does not automatically pass to the next. A family may have designed intricate legal structures for its assets yet have no plan for preparing the people who will one day steer those assets.

    Perhaps this is exactly where the paths of two families diverge. Some fortunes erode by the second or third generation, while others remain standing even after major upheavals. The real question is not “What will reach the next generation?” It is “Has the next generation been prepared to preserve family wealth and to steer what it receives?” In this Genar article, we address that question.

    When Three Lives Rest on One Asset

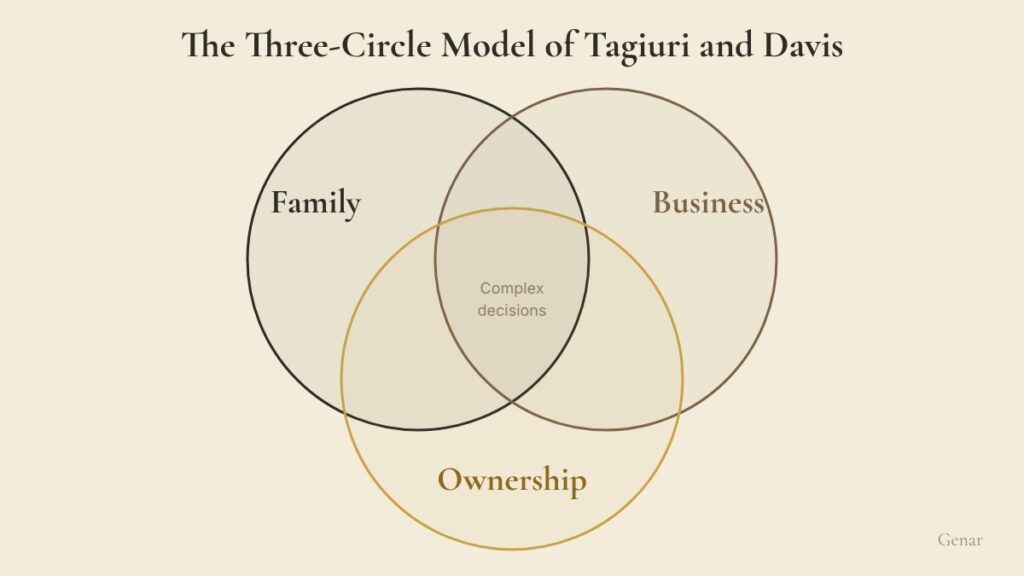
    A family that owns a family business or substantial wealth does not face a simple system. In 1978 at Harvard Business School, Renato Tagiuri and his doctoral student John Davis began developing a framework that would later become one of the best-known models in the field of family business: the Three-Circle Model of the family business.

    The framework separates three domains: family, ownership, and business. The idea first took shape in the work of two researchers in the 1970s, appeared in Davis’s doctoral dissertation in 1982, and eventually became one of the most-cited papers in the field through an article titled “Bivalent Attributes of the Family Firm” in 1996.

    The model’s core idea is simple and practical: not all family disputes are disputes between people; many are disputes between roles. A father who is the principal owner of the company says the final decision is his, while his son, the CEO, believes the authority to manage should rest with him. Both may be entirely reasonable from their perspective. The problem is not their personalities; it is a mistaken understanding of ownership and management, two concepts that must not be confused.

    As the family grows, this complexity grows with it. The number of owners increases, some enter the business, and some stay outside; under these conditions, a simple family relationship must answer emotional, ownership, and management concerns at the same time.

    Venn diagram of three overlapping circles labeled family, business and ownership, with complex decisions at the center where all three meet
    The Three-Circle Model of the family business, presented by Renato Tagiuri and John Davis

    This is exactly where structure becomes important. One person can be a family member, an owner and a manager at the same time. Another can be only a family member and owner with no role in management. A professional CEO can run the company with no family relationship at all. A sentence such as “This decision is in the family’s interest” is therefore not enough on its own. One must ask: in the interest of the family in which role, and in the interest of which generation?

    The Family Needs Governance Too

    When governance comes up, the mind usually goes to the board of directors and the bylaws. But a family that owns a business faces another question: how does the family itself make decisions?

    In the family business literature, this is called family governance. It means creating mechanisms for dialogue, decision-making, role definition and dispute management among the family, ownership and the business. The family council, the family assembly and the family charter are among the tools that more complex families use for this purpose.

    But the philosophy behind these structures matters more than their impressive titles: important issues should not be resolved for the first time in the middle of a crisis. What effect would it have on the business if one family member wanted to sell their shares? What disputes would arise if one person wanted to join the business and the others believed they lacked the necessary qualifications? These are not questions that can be answered with rules written in a moment of crisis. Good governance is not meant to eliminate disagreement; it is meant to keep disagreement from dragging the entire system down.

    But Structure Does Not Build People

    Now suppose the family has taken all these steps: it has set the rules, formed a board, refined the ownership structure and drafted the contracts with precision. All of this is necessary, but one question remains: are the people who will make decisions within this structure prepared for it?

    A structure can specify who has the right to vote, but it cannot give anyone the power of judgment. A contract can determine who owns what, but it cannot teach an heir when to hold an asset and when to change it. This is where the issue of succession shows itself.

    Being an Heir Is a Status; Becoming a Successor Is a Process

    Someone may become the heir to a large business merely by being born into a family. But no one becomes a leader by birth alone; leadership has to be built. The next generation needs the chance to make decisions, accept responsibility, face the results of its own choices, make mistakes and learn from them.

    In the family business literature, successor development is not merely the transfer of a title or shares; it is the simultaneous preparation of the family and the business to continue on their path in the next generation. An heir receives something, but a successor has acquired the ability to continue that path. The two concepts are not the same, and this is where intergenerational wealth transfer goes beyond a purely legal matter.

    Succession planning is usually a gradual path: first learning, then participating in some decisions, accepting real responsibilities, gaining greater authority at the next step and finally, if the person has shown the necessary competence, reaching a position of leadership. Successful succession does not happen on the day of the transfer; it must have been built years before.

    Financial Literacy Is Not Enough

    Suppose the next generation knows what a company is worth, what a balance sheet is and what return an asset yields. Does this knowledge mean readiness to steer wealth? Not necessarily. In the real world, important decisions do not always have a single right answer or a clear formula. What if the market crashes? What if the best economic decision conflicts with the wishes of part of the family?

    This is where financial literacy differs from competence in steering wealth. Financial literacy helps a person understand the numbers; competence helps a person exercise judgment when the answer is not known in advance.

    Wealth Is Not Always Visible in Financial Statements

    One key concept in family business research is socioemotional wealth: the values a family derives from owning and controlling the business that appear in no financial statement, such as family identity, control, belonging and the continued presence of the family.

    Luis Gómez-Mejía and his colleagues examined this concept in a well-known 2007 study of family olive oil mill owners in southern Spain. They showed that, to preserve this kind of wealth, families sometimes make decisions that look purely risky from an economic standpoint. The families chose between joining a cooperative (less business risk but loss of family control) and remaining independent (higher risk but retained control), and a large share preferred independence.

    Suppose a family receives a very large offer to sell its company. Financially, selling may be the best option, yet the family refuses. This decision is not necessarily irrational. Perhaps the company is not merely an asset to them; it is part of their identity, their name is on it and their history was formed within it. Before judging a family’s decision, ask what that family considers valuable. Sometimes the answer is not money.

    When Values Are Not Defined

    The problem begins when a family has never had a real conversation about its values. In such circumstances, in every dispute each person will hold their own definition of the “family’s best interest.” One member believes the company should be preserved because it is the family legacy. Another holds that the father was a risk-taker oriented toward growth and would have changed the company if he were alive today. Both consider themselves loyal to the legacy; only their definitions of legacy differ.

    For this reason, family values should not be merely a pretty sentence on the wall; they must show themselves in real decisions. What must never be sacrificed? If a conflict arises between preserving the legacy and building the future, which takes priority? Such conversations may seem unnecessary on calm days, but they are vital precisely for difficult days.

    Three Families, Three Different Lessons

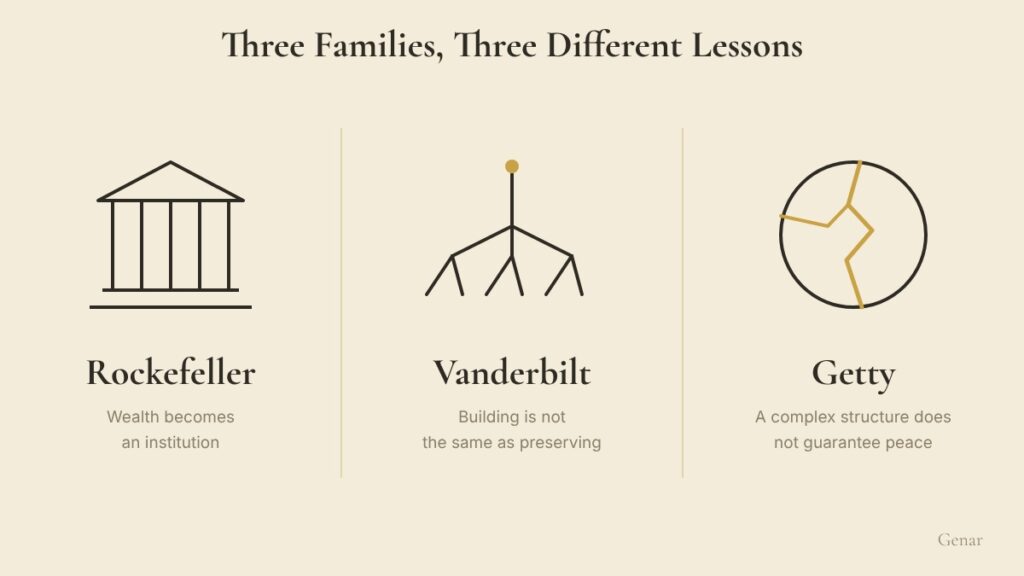
    The history of wealthy families offers no definitive formula for continuing a family business. However, three stories in particular clarify the question of intergenerational wealth transfer: the Rockefellers, the Vanderbilts and the Gettys. All three built immense fortunes, yet each carries a different lesson about how that fortune endures.

    Three line icons side by side: a columned building for Rockefeller, a branching tree for Vanderbilt and a cracked circle for Getty
    Rockefeller turned wealth into an institution. Vanderbilt showed that building and preserving are different skills. Getty showed that a complex structure does not by itself prevent disputes.

    Rockefeller: When Wealth Becomes an Institution

    John D. Rockefeller, founder of Standard Oil, built one of the largest fortunes in American history. But his story is not only about how much money remained for later generations. In 1913, the Rockefeller Foundation was established with a mission the foundation says has not changed since its first day: to promote the well-being of humanity throughout the world.

    Between 1913 and 1929, the Rockefeller family devoted substantial capital to the foundation, which, by its own figures, has distributed more than $26 billion in philanthropic capital worldwide over more than a century.

    The interesting point is that Rockefeller did not think only about “holding on to money.” Part of his wealth entered an institutional structure meant to serve a specific purpose, independent of any one person’s lifespan. The lesson of this story is not to establish a charitable foundation. The deeper lesson is that wealth can shift from a personal asset to an institution with a purpose and a time horizon independent of any one individual. The larger question than “Who owns it?” is “What is meant to remain after the owner?”

    Vanderbilt: When Building and Preserving Are Two Different Skills

    Cornelius Vanderbilt started in shipping, then moved into railroads and ultimately, by building the New York Central railroad empire, created one of the largest personal fortunes of nineteenth-century America. At his death in 1877, his estate was estimated at about $100 million, a figure that at the time exceeded the U.S. Treasury’s holdings. His son William Henry, who inherited roughly 95 percent of this fortune, not only preserved it but doubled it in less than a decade.

    The Vanderbilt story is not one of failure immediately after the founder. It is a story of serious crisis in later generations. After William Henry died, the fortune was split among his children; part of the next generation lost interest in the railroad business, and estate costs and a lavish lifestyle rose. According to historical accounts, when about 120 Vanderbilt descendants gathered in 1973 at the university Cornelius himself had founded, not one of them was a millionaire.

    Behind this lay a combination of dispersed ownership, changing economic conditions, an expensive lifestyle and the growing distance of later generations from the process that had created the wealth. The skill of building wealth is not the same as the skill of preserving it. Cornelius had to make decisions under competition and uncertainty; later generations encountered only the outcome of a path, not the difficulty of building it.

    Getty: When Great Wealth Builds a More Complex System

    1. Paul Getty built his immense fortune mainly in the oil industry. But the story of the Getty family is less about “preserving or losing money” than about the growing complexity of ownership, trust structures and family relationships between generations. The Getty family trust, formed in 1934 with about $3.3 million, became, after he died in 1976, the center of one of the most contentious family disputes in wealth history.

    According to Fortune magazine’s reporting from that era, Getty’s children and grandchildren entered a long legal battle over control of roughly $4 billion in assets and the way the trust was run. The battle even involved the rights of descendants not yet born, and it finally ended in 1985 when the trust was divided into several smaller parts among the different branches of the family.

    As the number of stakeholders grows, the question shifts from “How much money do we have?” to “Who decides, who has control and, if the family disagrees over the interpretation of ownership, who arbitrates?” The Getty story shows that a complex legal structure is not, on its own, a guarantee against disputes. Without governance, dialogue and clear rules, the structure itself can become part of the problem.

    From Three Stories to One Pattern

    The Rockefeller, Vanderbilt and Getty stories are not identical, but together they make one point clear: in each generation, wealth faces a different problem.

    The first generation is usually occupied with creating value: how does one build something that does not yet exist? The next generation must learn to steer well something it did not build itself. In later generations the question grows more complex: how does one build a shared path amid multiple owners and differing interests? For this reason, intergenerational transfer is not an “event”; each generation must prepare for its own particular problem.

    Four Layers That Must Be Built Together

    To turn this discussion into a practical framework for preparing the next generation to manage wealth, we can see it in four layers.

    1. Understanding

    The next generation must know how this wealth was built, what decisions drove it, what risks were taken and what mistakes were made. This is the difference between knowing an asset’s value and understanding its story.

    2. Competence

    Knowing is not enough; the next generation must have the chance to make decisions. The path is usually gradual: learning, participation, responsibility, authority, leadership. The goal is not for the next generation to copy the founder. The goal is for them to create value in their own time, under their own conditions.

    3. Governance

    When a family grows, the family relationship is no longer enough to resolve every issue. It must be clear who owns, who manages, who makes the final decision and how disputes are resolved.

    4. Meaning

    Ultimately, the family must know why it wants to continue this wealth. Is the goal only to preserve the value of the assets? Is creating opportunity for the next generation more important than ownership? Does “legacy” mean preserving exactly what the founder built? Or does it mean preserving the ability to create something valuable in every generation?

    These questions have no single answer, but a family that has not talked about them will likely be forced, in the hardest moment, to find answers on the spot.

    Owner or Steward?

    Another useful concept in this discussion is stewardship. Stewardship theory was proposed by James Davis, David Schoorman and Lex Donaldson in 1997 as a counterpoint to the prevailing view of the manager as a purely self-interested individual. They showed that under the right conditions, people can see themselves as serving the long-term interests of the organization and the collective, not only their personal interests.

    For wealthy families, this concept raises an intriguing question: are they the owners of these assets or their stewards for the future? These two views produce different decisions. If ownership is only an individual’s “right,” decisions are based on personal interest. But if ownership is joined by stewardship, another question enters: what does this decision mean for those who come later? Stewardship adds a time horizon to the decision without depriving the owner of the freedom to choose.

    A Simple Test for Families

    Suppose you own a business or a substantial part of the family wealth. Ask yourself these five questions:

    Does the next generation know how the family wealth was built?

    Has it ever had the chance to make real decisions and experience their results?

    Can it distinguish among the roles of “family member,” “owner” and “manager”?

    Has our family discussed possible future disputes before they occur?

    If the next generation has to change part of what we have built, does it know what must be preserved and what can be changed?

    If the answer to some of these questions is “no,” it does not necessarily mean failure. But it is an important sign that part of the transfer architecture has not yet been built.

    What Intergenerational Wealth Transfer Must Carry

    The question of wealth transfer cannot be solved with a document or a legal structure alone. These tools are necessary, but they are only part of the solution. Alongside assets, other things must also be transferred: knowledge for understanding, competence for making decisions, governance for managing complexity, and meaning for knowing why this path should continue.

    At first glance, the question is what intergenerational wealth transfer should transfer. At second glance, the question is what system must be built so that the next generation can make sound decisions with what it receives. These two questions are not alike, and this very difference separates one family’s path from another’s. In Genar’s articles on family and wealth, we have explored this subject from other angles as well.

    From Wealth Transfer to an Architecture of Continuity

    A family may use the best lawyers, financial advisors, and investment managers, benefit from a precise ownership structure, and have all contracts properly concluded. But if the generation that will make the decisions has not been prepared for that responsibility, part of the problem remains unresolved. On the other hand, educating one generation is not enough on its own either. If roles are unclear and family members have not discussed shared values and the future, even capable people may fail to be productive within a dysfunctional system and may fail to chart a sound path forward.

    Continuity of a family business is therefore not the product of a single element; people, structure and meaning must be designed together. This is where wealth transfer shifts from a legal event to an intergenerational project. The question for a family thinking about the future is not only “What are we leaving to our children?” The harder question is this: if everything is placed in their hands tomorrow, will they be prepared for the decisions they must make after us?

    A contract can transfer ownership, a structure can regulate power, capital can create opportunity, but competence must be built, governance must be designed and legacy must be given meaning.

    Perhaps the most lasting thing one generation can leave the next is not the wealth itself but the ability to build a future in which that wealth can continue to create value. This is the point where Genar’s approach to preparing the next generation begins.