Tag: intergenerational Wealth Transfer

محور اصلی گنار؛ هر مقاله‌ای که درباره‌ی رسیدن ثروت از یک نسل به نسل بعد است

  • Four Decisions for a “Why”

    Four Decisions for a “Why”

    When an art collection passes from one generation to the next, the new owner inherits more than a few artworks and the papers that prove they own them. They must decide what to keep, how to protect it, when to share it with others, and whether to sell. Knowing an artwork’s price and specifications is not enough to make these decisions. The real question is whether the heir knows why a work entered the family’s collection and what it has meant to the family.

    This Genar article draws on cultural capital theory and the experiences of families who own art collections to outline the four main decisions an heir faces when a collection changes generations. It shows why transferring ownership without transferring knowledge, and the logic behind how the family chose its assets, is not enough. It also shows how the next generation can develop the ability to judge and decide about the collection.

    Ownership can be inherited; judgment has to be learned

    In his essay “The Forms of Capital” (1986; in Handbook of Theory and Research for the Sociology of Education, ed. J. Richardson, Greenwood, pp. 241–258), the French sociologist Pierre Bourdieu describes cultural capital in three forms: lasting dispositions of mind and body, cultural objects such as books and paintings, and formal educational credentials. For our discussion, the difference between the first two matters most. You can hand an artwork to someone else, but ownership alone does not give them the ability to understand and enjoy it. That ability takes time, experience, and personal involvement. We call it “judgment.” It is the part of intellectual capital that helps an heir move from mere owner to steward.

    This difference matters for family art collections. An heir may own a work without knowing why the family bought it, what place it holds in the family’s history, or what should guide decisions about its future. Bourdieu did not write directly about family collections, so applying his framework here is this article’s own interpretation.

    Judgment is built from three questions

    Picture a painting that hung in your parents’ living room for years and now belongs to you. You know its frame, even the mark its nail left. But you don’t know what it is worth or who bought it, and if someone asked why it stayed in your family, you would have no answer. This situation is neither unusual nor rare.

    According to the Art & Finance Report 2025, the ninth edition of a joint study by Deloitte, the international audit firm, and ArtTactic, a leading firm in art-market research, data analysis, and advisory, about 61% of collectors have never discussed their collection with their heirs. Another 21% have made only informal references to it. In other words, the future owners of these works are unaware and unprepared. To decide about an artwork, an heir must be able to answer three questions:

    • Who owned the work, what is its history, and how well is its authenticity confirmed?
    • What are its market value and its insurance value?
    • Who chose it, and what place does it hold in the family’s history and life?

    Experts and appraisers can answer the first two. The third depends on the family’s own knowledge and narrative, and it underlies all four of the heir’s main decisions about the collection.
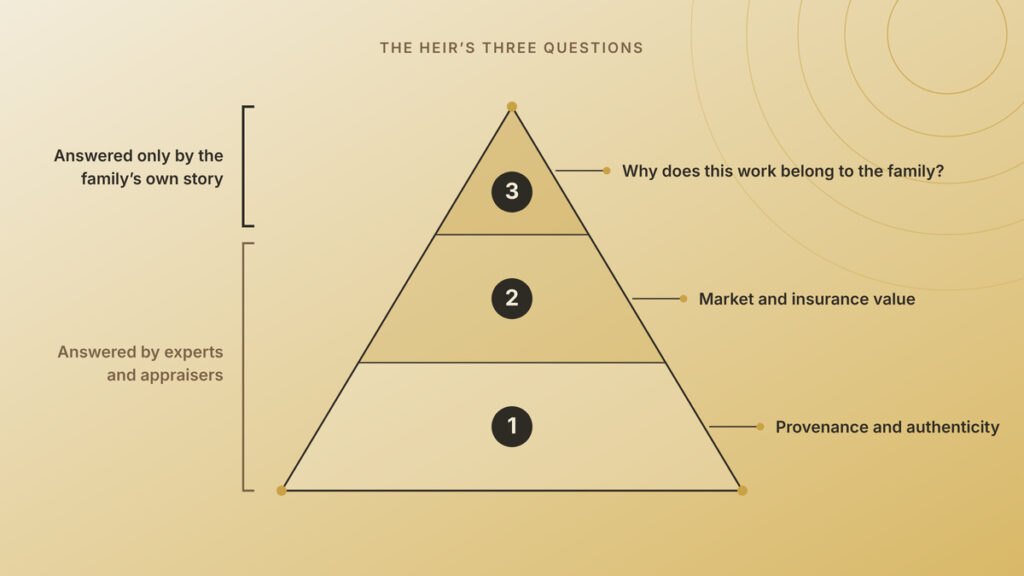
    A three-tier pyramid of the questions an heir faces about an artwork: provenance and authenticity, market and insurance value, and why the work belongs to the family. Experts answer the lower two; only the family’s own story answers the top one.
    Experts and appraisers can answer the first two questions, but the third depends on the family’s own understanding and narrative.

    The false assumption of automatic knowledge transfer

    Many people wrongly assume that a child who grew up beside the family’s artworks has naturally acquired the necessary understanding. Bourdieu also points to the family environment’s role in the implicit transmission of cultural capital. Even so, having a work in your surroundings does not necessarily mean you know why the family chose and kept it.

    This assumption is especially fragile when the heir grew up far from the family’s home or country, or when the work has been separated from the context that gave it meaning. In such cases, the heir may know the work yet remain unaware of the memories, conversations, and values behind its selection.

    This article suggests that part of the families’ silence in the Deloitte survey may come from this very belief: that the necessary understanding passes on by itself. This is an interpretation, not a direct finding of the survey.

    Three logics behind an art collection

    When we ask “why is it here?”, we don’t mean one reason alone. A collection can take shape for at least three kinds of reasons, and families usually pursue a mix of them. Each of the three families below illustrates one of these reasons especially clearly.
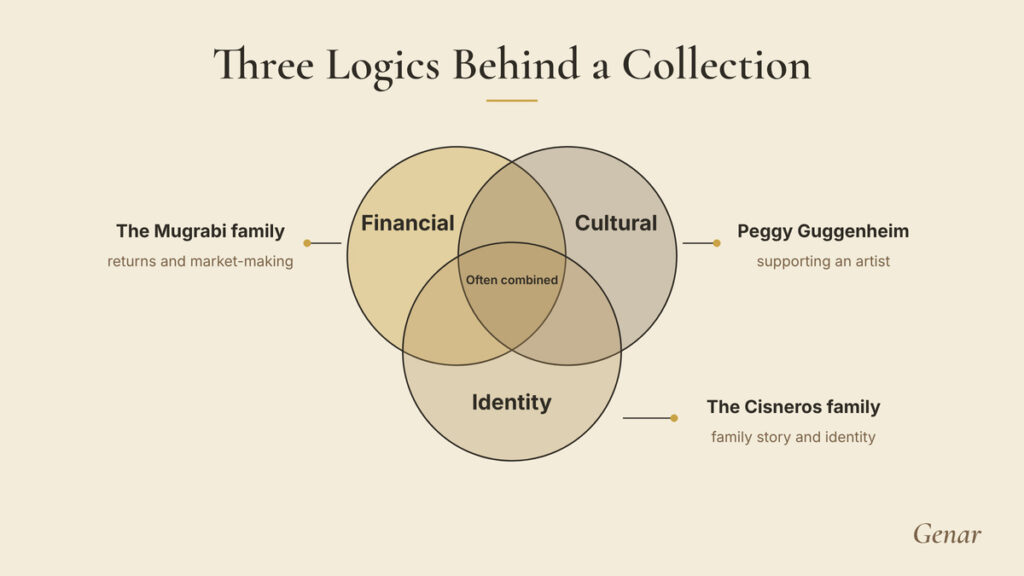
    A three-circle Venn diagram of the financial, cultural and identity logics behind art collections, illustrated by the Mugrabi family, Peggy Guggenheim and the Cisneros family. Families usually follow a mix of the three.
    There are at least three kinds of reasons for forming an art collection, and families usually pursue a combination of them.

    The financial reason: the Mugrabi family

    In 1987, at Art Basel, José Mugrabi, a textile trader who had spent his youth in Colombia, saw Andy Warhol’s paintings for the first time. By his own account, he felt something in these works that he had not felt in other art. Yet a 2014 account describes the family’s approach as openly financial. He and his sons, Alberto and David, held the largest collection of Warhol’s work outside the Andy Warhol Museum in Pittsburgh.

    Alberto called them “market makers,” because to influence the prices of an artist’s work, you have to hold a substantial number of that artist’s pieces. They took part in roughly fifty auctions a year. Nearly every work in their collection was for sale, and the family had no plans to build a museum for them (Don Thompson, The Supermodel and the Brillo Box, Palgrave Macmillan, 2014).

    The two generations’ tastes also differed: José liked Pop Art, while his sons favored younger artists such as Damien Hirst and Jeff Koons. Even so, the difference did not stop them from working together. When a collection rests on financial logic, aligned tastes are not necessary. The Mugrabis are, of course, an exceptional case. They operated with a very large inventory and a vast amount of buying and selling, which most heirs could not replicate.

    The cultural reason: Peggy Guggenheim

    In 1943, Jackson Pollock was a thirty-one-year-old painter working as a guard and preparator at the Museum of Non-Objective Painting, Solomon Guggenheim’s museum of abstract art. Peggy Guggenheim, Solomon’s niece, offered Pollock a contract with a monthly stipend so he could paint full time. She also commissioned a large mural from him for the entrance of her home (Guggenheim Museum, exhibition statement for Away from the Easel: Jackson Pollock’s Mural, October 2020). In 1951, she donated that same work to the University of Iowa.

    This is an example of the cultural reason a collection takes shape: supporting an artist early in his career. Two Guggenheims, two institutions, two different views of one artist.

    The identity reason: the Cisneros family

    From the 1970s, Patricia Phelps de Cisneros and her husband, Gustavo, built a collection of Latin American art, with roots in their homes in Caracas and New York. The collection’s stated mission is to increase understanding and appreciation of the diversity and complexity of Latin American art.

    In 2016, the family donated more than a hundred modern works to the Museum of Modern Art (MoMA) in New York, along with funding for a research center. In 2018, it divided more than two hundred further works among six museums in Latin America, the United States, and Europe. The collection itself described this as part of a long-term, global initiative by the Cisneros Phelps family (Andrew R. Chow, New York Times, 2018). The collection tells a story of the family’s identity: where we came from, and what we want others to see in it.

    What separates these three kinds of reasons is how easily each can be expressed and recorded. A financial reason can be measured in numbers and performance. The other two have to show themselves through narrative, mission, or the family’s behavior. Peggy Guggenheim and the Cisneros family recorded the reasons for their choices in visible acts: a contract, a declared mission, a series of donations. As a result, their heirs can know these reasons rather than guess them.

    The logic of keeping an art collection

    The painting is still in the living room, and the first question seems simple: keep it or sell it? Before answering, remember that keeping, despite appearances, is not a cost-free decision. The work needs suitable space, controlled light and humidity, insurance, and specialist care. Not deciding is also a form of keeping, except that no one has chosen it consciously. The core question is: why should the family keep this work?

    The financial return of art, and its limits

    If the answer is only financial, it is not a strong one. Three finance researchers, Arthur Korteweg, Roman Kräussl, and Patrick Verwijmeren, studied the prices of paintings that sold more than once over several decades. In their paper “Does It Pay to Invest in Art? A Selection-Corrected Returns Perspective” (Review of Financial Studies, 2016), they showed that common art price indices overestimate true returns. Works whose prices have risen get resold more often, so they carry more weight in market data. Put simply, these indices mostly see the winners.
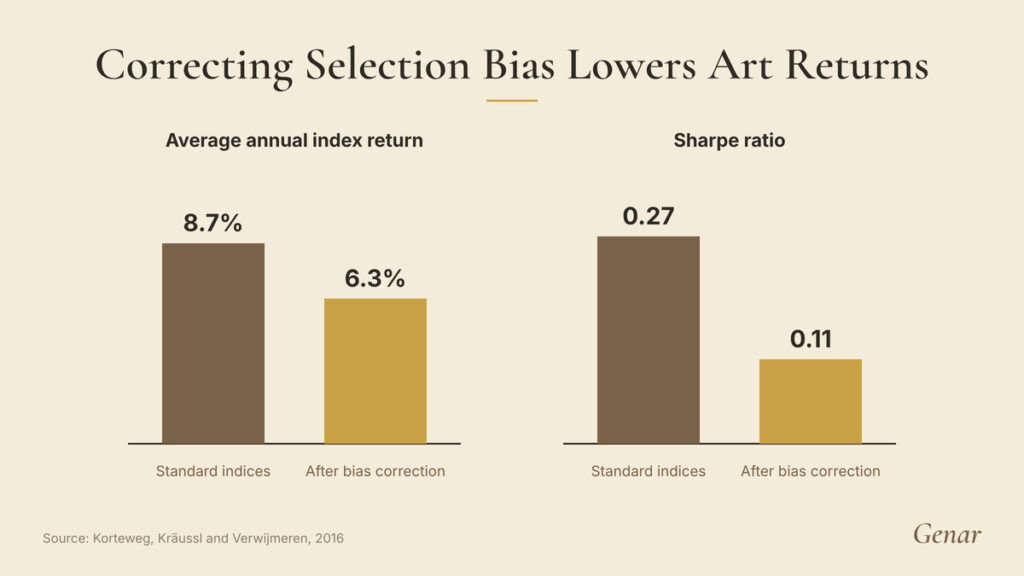
    Bar chart: after correcting for selection bias, the average annual painting-index return falls from 8.7% to 6.3% and the Sharpe ratio from 0.27 to 0.11. Source: Korteweg, Kräussl and Verwijmeren, 2016.
    Put simply, these indices mostly see the winners.

    Once this bias is corrected, investing in a diversified portfolio of paintings looks far less attractive, though deliberately choosing particular styles or artists can still create value.

    The 2025 Deloitte report strikes a similarly cautious note: the case for art as a standalone investment is more open to doubt than before, although art may help preserve capital and hedge against inflation. So the notion that “an artwork always gets more expensive” has no firm foundation. That does not make art worthless. It shows that the reason to keep a work need not be its financial return.

    Non-financial values in preserving family collections

    To answer this, we can draw on research into family firms. In “Socioemotional Wealth and Business Risks in Family-Controlled Firms: Evidence from Spanish Olive Oil Mills” (Administrative Science Quarterly, 2007), Gómez-Mejía and his colleagues showed that families are sometimes willing to accept greater financial risk to preserve family control and identity. They called these non-financial aspects “socioemotional wealth”: the emotional, identity-related, and social values tied to family ownership. We explore this research further in the Genar article “Wealth Transfer Is Not Just Money Transfer.”

    This research concerns family firms, not art collections. Still, an important point follows. A family that keeps a work despite a modest financial return is probably paying for something that matters to it beyond the price. That something may be part of the family’s identity, memory, or cultural heritage. When no one has stated such a reason, the cost of keeping may gradually start to look like wasted resources, and anything whose why is unclear is more vulnerable to a decision to sell.

    This matters even more for the next generation. In Deloitte’s 2025 survey, financial motives matter less to next-generation collectors than to earlier ones, while identity, legacy, and cultural impact stand out. An heir who doesn’t see financial return as reason enough to keep a work needs another reason. If the previous generation hasn’t passed one on, the heir must discover or rebuild it.

    Valuing and insuring an art collection

    Suppose the family has decided to keep a painting. One of the first steps is to take out an art insurance policy, and a policy needs a specific figure. But relying only on auction prices can lead to insuring a work for less or more than its true value. Moreover, 63% of collectors have little trust in art-market data (Deloitte, 2025). Two different questions arise here:

    • What is the work worth?
    • What is it worth to the family?

    The first concerns financial valuation. Market prices cannot answer the second. When no one has recorded why the collection formed, price becomes the only yardstick available to heirs, and given the art market’s limited transparency, it is not always reliable.

    Randall Willette, an art-collection advisor, points to the consequences of families lacking clear rules in “Establishing Sound Governance for a Family Art Collection” (WealthBriefing, February 19, 2013). In such conditions, families may make decisions ad hoc and without enough consultation, and emotions that weigh too heavily can later bring challenges.

    Picture two siblings who disagree about a painting. One wants to keep it, and the other prefers to sell. If the only information they share is price, the dispute narrows to arguing over numbers. Which appraiser? Which auction? The price from which year? Meanwhile, the central question, the work’s place in the family’s history, goes unanswered.

    Lending and donating: the collection’s role in public space

    Suppose a museum asks to borrow a painting from the family collection for a few months for an exhibition. The family can lend the work or, if it wishes, donate it to a cultural institution. This is the first decision that takes the collection beyond the family’s private sphere and involves others.

    At this stage, the work’s provenance becomes more important. Who held the work and how it changed hands help confirm its authenticity and credibility, and they also clarify its historical significance (Randall Willette, 2013). But the more important question is: what is this work meant to say to others?

    According to the Deloitte survey, only a limited share of collectors intend to donate their works to public museums. Younger collectors, however, show growing interest in philanthropy through art. This shift highlights the role of next-generation motives in decisions about the collection’s future.

    An heir may want to place a work with an institution whose mission or values match their own, even if that choice differs from the original owner’s motive. That difference is not necessarily a problem, because the next generation is not meant to continue every earlier decision unchanged. The problem begins when the heir does not know why the collection formed. In that situation, the change of course comes from not understanding the legacy rather than from knowing it.

    Selling, and the logic of leaving a collection

    Unlike keeping or lending, selling is usually a decision you cannot reverse. Even so, selling an artwork does not necessarily mean failing to preserve the family’s legacy. Sometimes shifting priorities, a need for liquidity, or a change in how the family sees the collection makes selling a reasonable decision.

    The Deloitte report also points to the art market’s limitations, including low transparency, limited liquidity, and the difficulty of assessing prices. In such a market, an attractive offer alone is not enough to decide. Besides price, the heir must be able to assess the work’s place in the collection and the reason the family kept it.

    Two heirs may sell a work at the same price for entirely different reasons. The first knows why the work entered the collection and has concluded that this reason no longer holds as it once did, so selling reflects an informed assessment. The second knows nothing of the work’s background or its place in the family and sells simply because a good offer arrived. The outward result is the same in both cases, but only the first heir decided based on understanding.

    The point is not that the heir must keep every work. It is that they can explain why they keep or sell it. Even keeping a work out of habit alone, without understanding its place in the collection, can be as unfounded a decision as a hasty sale.

    Four decisions and one shared logic

    Keeping, valuing, lending or donating, and selling are not four independent decisions. Each rests on the understanding the heir has gained of the work and its place in the collection. If that understanding is missing, its weakness shows at every stage of decision-making.
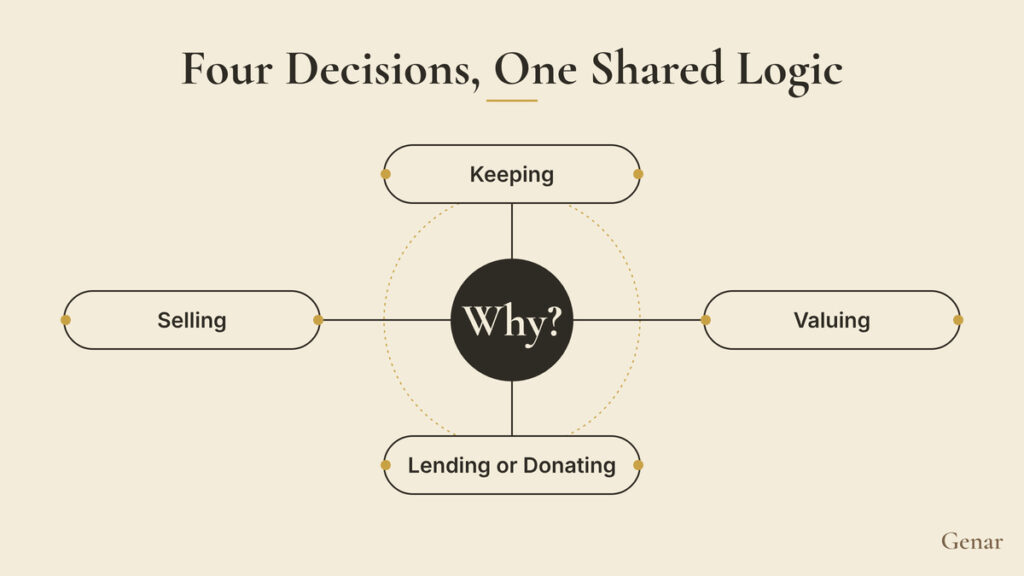
    A diagram of four decisions, keeping, valuing, lending or donating, and selling, all arranged around the central question “Why?”
    Keeping, valuation, lending or donating, and selling are not four independent decisions. Each rests on the understanding the heir has gained of the work and its place in the collection.

    Passing on the why is not meant to oblige the next generation to repeat past decisions. This understanding should let the heir evaluate earlier decisions, change them when necessary, and take responsibility for their own choices.

    The difference between ownership and stewardship becomes clear here: ownership gives a person the right to decide, but understanding the collection’s logic lets them exercise that right knowingly.

    The Rockefeller family and MoMA: passing on the why through responsibility

    The Rockefeller family’s story with the Museum of Modern Art (MoMA) in New York shows how passing on a collection’s logic connects to the next generation’s real involvement. In 1929, Abby Aldrich Rockefeller, wife of John D. Rockefeller Jr., founded MoMA together with two friends, Lillie P. Bliss and Mary Quinn Sullivan.

    Abby’s interest in modern art differed from her husband’s taste. Junior was more drawn to sculpture, architecture, and old European crafts, and he created a separate institution to support those fields. This difference shows that even within one family, collections can form according to different logics and interests. (Rockefeller Archive Center; Abby Aldrich Rockefeller and Modern Art; Suzanne Loebl, America’s Medicis: The Rockefellers and Their Astonishing Cultural Legacy, 2010)

    In 1935, Abby donated about 181 paintings and drawings, nearly all of her modern art collection, to MoMA. Her other collections also went to institutions suited to their nature and the context in which they formed. Sculpture and decorative arts went to The Metropolitan Museum of Art and The Cloisters, Japanese prints to the Rhode Island School of Design, and her American folk art collection to Colonial Williamsburg. Financial value alone did not decide where a work went; the type and cultural standing of each collection mattered too. (Rockefeller Archive Center; Abby Aldrich Rockefeller, 1874–1948)

    The next generation’s role also went beyond receiving assets. Nelson Rockefeller became president of MoMA in 1939, ten years after the museum’s founding. David Rockefeller, the family’s younger son, joined the museum’s board of trustees in 1948 and later chaired it. David had known art since childhood but was at first skeptical of contemporary art. Alfred H. Barr Jr., MoMA’s first director, introduced him to contemporary artists and movements. (ARTnews, 2017; Helen Stoilas, The Art Newspaper, March 20, 2017)

    This experience matters for intergenerational transfer in three ways. The family entrusted the logic behind the collection to an institution with a clear mission. The next generation took on real responsibility in running that institution. And becoming familiar with the previous generation’s outlook did not mean repeating it unquestioningly. David could be skeptical of contemporary art, yet his position let him learn, examine, and form an independent judgment.

    The Rockefellers’ experience cannot serve as a general template for all families. The scale of their wealth, their access to cultural institutions, and their historical circumstances were exceptional. Even so, the example shows that an art collection’s legacy transfers more deeply when understanding and responsibility reach the next generation alongside ownership.

    How knowledge and responsibility pass within the family

    Art advisors, appraisers, insurers, and lawyers can play an important role in managing an art collection. They provide specialist information on authenticity, financial value, storage conditions, and legal requirements. But this information alone does not tell the heir why the family chose a work or what role it was meant to play. That understanding has to form within the family and pass on there.

    Families should not put this process off until ownership transfers. If the heir first meets the collection after the owner’s passing, or when the family divides its assets, they will have limited opportunity to learn its history and the logic of past decisions. Knowledge and responsibility should begin passing on earlier and enter the next generation’s experience gradually. Three steps can help.

    Record and explain the logic behind the choice of works

    The current owner should be able to explain why they bought, kept, or valued each work. This doesn’t require a detailed written history. Sometimes it is enough to know why someone chose a work, how it related to the family’s values, or why the family preserved it over the years, and that gives the heir decisive information. Recording this matters most before memories and details fade.

    Involve the heir gradually in decisions

    Theoretical familiarity with the collection is not enough to develop judgment. Before ownership fully transfers, the heir should take part in real but limited decisions. For instance, they might give their view on buying a new work, choosing where to keep a piece, lending a work to an exhibition, or allocating a maintenance budget. This lets them see the consequences of their choices and gradually take on more responsibility.

    Write the family’s art collection policy

    The family can prepare a written document that sets out the collection’s purpose and the principles for deciding about it. It should answer questions such as why the family keeps the works, what criteria guide acquisitions, under what conditions it would sell, how it will transfer or donate works, and what each family member is responsible for. The process has value beyond the final document: the conversation and agreement needed to produce it help clarify how the generations’ views differ.

    These steps are not meant to impose the current owner’s taste and decisions on the next generation forever. The aim is for the heir to understand the collection’s logic first, then decide whether to continue, adjust, or set it aside. In the end, the quality of an art legacy’s transfer depends not only on ownership documents but also on how ready the next generation is to accept responsibility and exercise independent judgment.

    Exercise: the column missing from the provenance

    An artwork’s provenance usually records the year a given person or institution held the work and how it passed from one owner to another. This information matters for verifying authenticity and credibility, but it usually doesn’t explain why someone chose or kept the work.

    To test how much that matters, choose a specific work from the family collection and write out its provenance as a table. Then add a column titled “Why?” and record the reason the family bought, kept, or transferred the work.
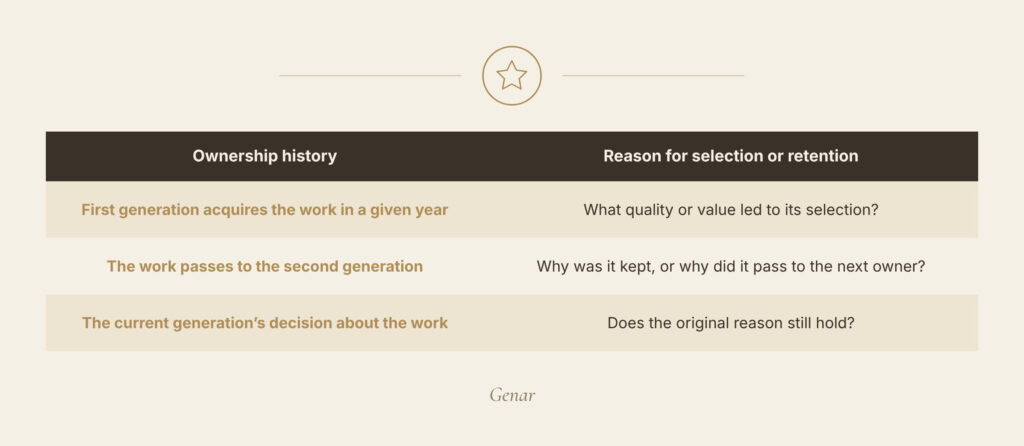
    A two-column table with three rows of an artwork’s ownership history and, beside each, the question of why it was chosen or kept.
    To test the importance of this information, you can choose a specific work from the family collection and write out its provenance in a table.


    Next, ask the next generation of the family to write down, without consulting the current owner’s explanations, their own sense of why the work is in the collection. Comparing the two accounts can show how much of the collection’s founding logic has passed on and which parts remain unspoken.

    This exercise is not meant to judge past decisions as right or wrong. Its aim is to show the gap between knowing why a work belongs to the family and understanding why that same work has become part of the family’s art legacy.

    From ownership to responsibility

    This issue is not limited to the transfer of art collections. Other Genar articles have repeatedly noted that in intergenerational wealth transfer, assets may pass from one generation to the next, but the ability to manage, preserve, and grow them does not pass on automatically. That ability requires understanding, experience, and the next generation’s gradual involvement.
     

  • Wealth That Doesn’t Show Up in Financial Reports

    Wealth That Doesn’t Show Up in Financial Reports

    In years of crisis, intergenerational wealth transfer is more than moving assets. It answers one question: after all these years, does the heir still see the family’s wealth as their own?

    At the end of the film A Separation, Termeh must choose between her father and her mother. We see her in a home where three generations live under one roof: a grandfather who belongs to the first generation and can no longer move on his own, a middle generation torn between staying and leaving, and a third generation that has to choose. The film ends before we hear Termeh’s answer. The same scene plays out in families that own a business: the first generation built, the second hesitates between staying and leaving, and the next generation, without realizing it, is building a world of its own.

    Crises slowly open distances between generations: a distance of geography, a distance of experience, and a distance of language.

    This Genar article examines all three distances and offers ways to close them. At the end, you will find a quiz with a few questions you can raise at the family dinner table this week.

    What Is a Family’s Real Wealth?

    When people talk about family wealth, they usually mean financial statements and assets such as property, shares, and cash. But James Hughes (Family Wealth: Keeping It in the Family, Bloomberg Press, 2004), who has worked with multigenerational wealthy families for three decades, defines it differently. In his view, a family’s real wealth is the human, intellectual, and social capital of its members. Financial capital is not the goal here; it is a tool for growing those three forms of capital. This definition matters especially for wealthy Iranian families who have lived under the pressure of crisis in recent years, because it shows that the main danger does not always lie in the market.

    The Family’s Three Forms of Capital: Human, Intellectual and Social

    Social capital is the family’s network of relationships: the people who have worked with the family for years, the trust of a market and an industry that took years to earn, and a name, or more precisely the good reputation, that opens every door. No one builds this capital overnight, and no one inherits it from a distance.

    Intellectual capital is the knowledge and judgment that preserve and grow wealth: knowing where the wealth came from, the ability to make decisions under pressure and a horizon that sees ten years ahead. This is what turns an heir from an “owner” into a “steward.”

    Human capital is the family members’ ability to stay together: trust, dialogue between generations, and each person’s readiness for the responsibility entrusted to them. The other two forms of capital stand on this foundation.

    The important point is that none of these three forms of capital appears in the financial statements. A family can be financially healthy and, at the same time, be losing all three.

    How Do Crises Create Gaps?

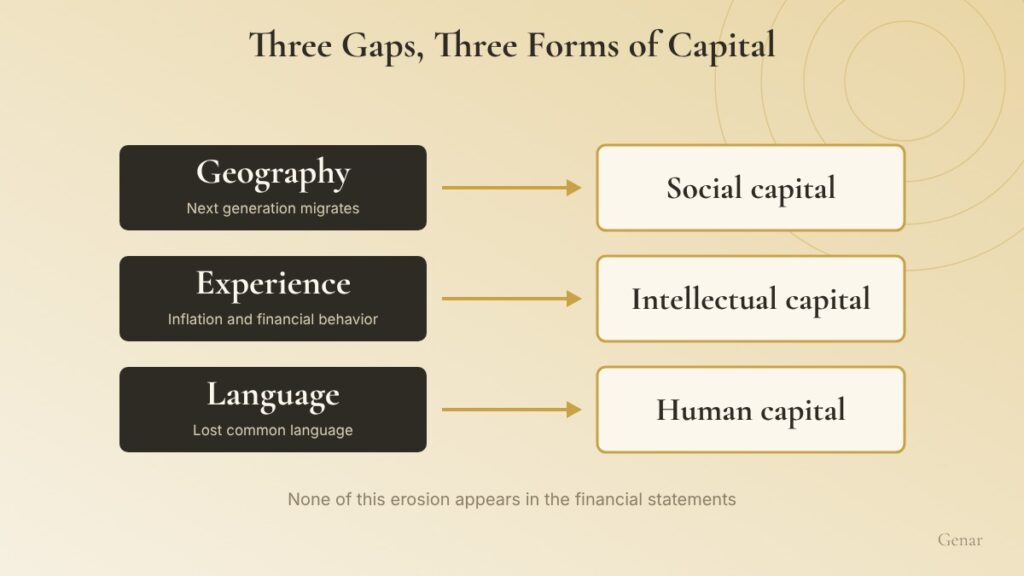
    Crises are usually measured in the language of assets: a falling rial, market volatility, sanctions. But their more hidden effect changes the heir’s relationship with wealth. Migration, chronic inflation, and changing lifestyles pull the new generation away from the family’s wealth, and each distance erodes one of the three forms of capital.

    Diagram of three rows: geography (migration of the next generation) leads to social capital, experience (inflation and financial behavior) to intellectual capital, and language (a language gap) to human capital, on a cream-to-gold gradient background
    Each distance erodes one of the family’s three forms of capital, and no financial statement records it.

    This erosion is slow; it does not show up in any financial report or get recorded in any month of the year. Yet trust has worn thin, or the heir no longer knows where the wealth came from. That is why preparing heirs must begin before financial warning signs appear and must be part of a family financial culture to which every generation contributes.

    Geography: Heirs’ Migration and the Erosion of Social Capital

    The migration of heirs is the first and most visible gap in social capital, the relationships and trust on which family wealth stands. Families usually prepare for someone’s absence before that person even leaves. Decisions start being made without them, and the person gradually adapts to this as well.

    Migration Among Entrepreneurs and Senior Managers

    If you think this is a story about young people with nothing to lose, the numbers say otherwise. In the survey of the Iran Migration Yearbook 1401 (2022–23), the desire to emigrate among entrepreneurs and senior managers was higher than in most groups, reaching about 70 percent. Those who have the most capital to manage think most about leaving.

    Leaving is usually one-way, too. In the same yearbook, 62 percent of Iranian emigrants had firmly decided not to return, and only 14 percent were certain they would go back. These figures predate the war, the heavy sanctions and the blockade.

    For an ordinary family, migration means leaving. For a family whose wealth is rooted in this soil, it means being split in two. But what suffers most are the relationships built over decades: the market’s trust and the credibility that opens the way to every deal. None of it fits in a suitcase, and none of it can be inherited from a distance.

    A Distant Heir or an Absent Heir?

    An heir can become absent without migrating. Someone who receives the reports and only skims them will one day own something they never had a role in running. This absence happens without a single flight.

    On the other hand, a member of the next generation who lives outside Iran can also be the family’s greatest asset: someone who has tested themselves and their skills outside the shadow of the family name and sees beyond the usual routine of the family business. The experience of one generation of the Grant family illustrates this well. The difference between these two heirs is not geography. It is the answer to one question: can this heir be trusted with a real decision and the responsibility that comes with it?

    Responsibility Instead of Video Calls

    When an heir to a family business emigrates, the usual response is to keep minimal contact: a weekly call, sending reports and passing on major news. This contact is valuable, but it does not close the gap, because the heir is only a listener. They know what happened, but nothing depended on their decision. People become attached to things whose outcomes depend on them, not to things they are merely informed about.

    Social capital works the same way. The family’s network (partners, suppliers, bankers and long-serving managers) does not survive on names alone; its continuity depends on decisions and accountability.

    If this network knows the heir only as “So-and-so’s son or daughter who lives abroad,” it sees them only as a name from the past. If it sees them as someone who has made a decision on a matter and taken responsibility for it, it sees a person it can work with in the future.

    What Makes Responsibility Real?

    Responsibility that exists only on paper is empty, and the heir quickly realizes it. For responsibility to be real, four conditions are needed:

    • Real decision-making: The heir does not give an opinion; they make the decision. If the elders always have the final word, the heir realizes their opinion was a formality.
    • Tangible results: The decision must produce a result that can be measured, whether it turns out good or bad. Responsibility that is never evaluated is practice, not responsibility.
    • A defined domain: The area that belongs to the heir must have clear boundaries. “Keep an eye on everything” gives no one responsibility, but “This part is yours” gives a person practical responsibility.
    • A regular schedule: Reviews at fixed intervals, for example, at the end of each quarter. Scattered decisions do not build a relationship; they create an irregular rhythm.

    Inflation, the Young Generation’s Experience and the Erosion of Intellectual Capital

    The second gap is not created by geography; it comes from experience. Two generations can sit in the same house and eat together, yet each has lived through the crises differently. This difference stems directly from intellectual capital: from how the heir sees wealth, what horizon they set for it, and what they rely on at the moment of decision.

    Experience Teaches; It Does Not Preach

    Most families begin preparing heirs with talk: about thrift, honesty, the hardship of building. But an heir learns less from what they hear than from what they live through.

    In A Separation, Termeh tips the gas station attendant, and Nader asks her to get the money back. Reluctantly, Termeh gets out of the car, argues with the man, and takes the money back, and Nader smiles and tells her to keep it. Her father gave her no lesson about right and wrong; she learned it with real money, a real person, and a little real fear. The film also shows the bitter side of this experience: Termeh, who learned honesty from her father’s words, lies to the judge at the end to protect him, because she learned concealment from his actions.

    This is not merely an observation about parenting. Ulrike Malmendier and Stefan Nagel, two leading economists, showed in “Learning from Inflation Experiences” (Quarterly Journal of Economics, 2016) that people give too much weight to the inflation they have experienced themselves and build their financial decisions on it. The effect is stronger among younger people, because recent experience makes up a larger share of their lives. Put simply, each generation understands money through the crisis it has seen, not through what it has been told.

    A Generation That Has Seen Only Inflation

    Imagine someone who is 25 today and has seen nothing but inflation. Since the Iranian year 1398 (2019–20), annual inflation has not fallen below 30 percent in a single year: from 34.8 percent that year to 45.8 percent in 1401 (2022–23), and in August 2026, point-to-point inflation reached 89 percent. Their entire adult life has taught one lesson: money does not last, and it should be turned into another asset quickly.

    An ISPA survey in Mehr 1402 (fall 2023) showed the same pattern across Iranian society. People over 50 preferred bank deposits more than others, those aged 30 to 49 favored land and housing, and young people leaned toward gold and coins. Three generations, three logics for the same money, and each logic comes from crises that generation lived through firsthand.

    For most families, this is only a question of preserving asset value. But in a family that built its wealth, a larger issue weighs heavily: what is at risk is intellectual capital, that is, judgment, horizon, and the ability to see ten years ahead.

    An heir who has seen only inflation may be right to prefer trading over building. Under these conditions, if they see the family’s wealth as something to be traded rather than something that was built, the long-term view that preserves wealth slowly fades.

    The Founder’s Behavior in Crisis: A Lesson Plan for the Heir

    Here we must look at the other side of the issue: in these years, what has the founder done in the face of crisis? If the heir has watched the elders move capital into gold and foreign currency at every piece of bad news, that is where today’s lesson came from, not from advice at the dinner table. But if they have seen part of the profits reinvested in the business during the hardest years, the lesson they learned will be entirely different.

    Neither behavior is necessarily wrong; avoiding risk in a crisis is sometimes the wisest choice. The point is that the heir sees the behavior but does not understand the logic behind it unless someone explains it. So the founder’s behavior in crisis needs to become more deliberate, and the reasoning behind it needs to be shared with the heir.

    How Can We Give the Heir Real Decision-Making Experience?

    Building cannot be taught through advice alone; its experience can only be passed on, as in the gas station scene in A Separation. For families that own a business, this means a small but real investment decision with four features:

    • Real money: The amount can be small, but it must be real money, not a simulation. When the heir knows a mistake has a cost, they think differently.
    • A long horizon: The decision’s outcome should unfold over years, not weeks. The goal is for an heir who has made only short-term decisions to also experience the fruits of patience.
    • Shared review of results: Every few months, the older and younger generations should review the outcomes of decisions and the reasons behind them.
    • Reviewing earlier generations’ mistakes: When the founder talks about their own wrong decisions, the heir understands that making mistakes is part of building.

    The Lost Common Language and the Erosion of Human Capital

    The third gap is the quietest of all. In many families, two generations live side by side for years without understanding each other, and this erodes the family’s human capital: the gradual fading of trust, dialogue, and readiness to take on responsibility.

    In A Separation, Termeh is doing her Persian homework. The teacher has included an Arabic word in the list, and Nader insists that his daughter write its Persian equivalent, even if it costs her marks. The daughter is caught between her teacher and her father. Much the same happens at the dinner tables of business-owning families.

    The 70 Percent Rule: Fact or Myth?

    You have probably heard that 70 percent of fortunes are lost by the second generation. The number is repeated so often that few people have asked where it comes from.

    Researchers such as James Grubman (International Family Offices Journal, 2022) traced its origin and arrived at a study by John Ward (Keeping the Family Business Healthy, Jossey-Bass, 1987) that examined 200 family-owned manufacturing businesses in one U.S. state. But 70 percent did not show lost wealth either; it showed only that ownership of the business had not stayed in the family.

    So the number can be set aside, but the problem remains. The question is not what percentage fail; it is where failure begins and why.

    Wealth Is Lost at the Dinner Table

    The researchers who made the number famous also report a more important finding. Williams and Preisser (Preparing Heirs, Robert Reed Publishers, 2003) examined why transitions failed, although the raw data behind their research was never published. In 60 percent of cases, communication and trust within the family had broken down, and in 25 percent, heirs had not been prepared to take on responsibility. In other words, most fortunes are not lost in the market; their undoing is decided at the dinner table.

    The picture is the same in our neighborhood. In 2024, PricewaterhouseCoopers (PwC), one of the world’s four largest audit and advisory firms, surveyed the next generation of Dubai’s family businesses (NextGen Survey, Dubai edition). Half of them said one of the hardest parts of succession is that the current generation cannot or will not step back. Only 39 percent were sure their family had a succession plan. So in most families, succession in the family business is still not a plan; it is a conversation that keeps being postponed.

    A Values Gap or a Language Gap?

    This situation is usually called a values gap or a generation gap in business-owning families. But much of it is, at heart, a language gap.

    The founder built the business in a time of scarcity and relied on people; a contract was simply a handshake. The heir grew up with sanctions on one side and the internet on the other, and relies on data. Both want the business to endure; they simply talk about it in two different languages, and each assumes the other thinks the wrong way. Trust slowly declines, and with it, the readiness to take on responsibility.

    Reverse Mentoring: When Both Generations Are Teachers

    This problem has an old solution. In 1999, Jack Welch asked young employees at General Electric to teach senior executives how to use the internet. The practice later became known as “reverse mentoring,” and researchers such as Murphy (“Reverse Mentoring at Work,” Human Resource Management, 2012) studied its effect on learning across generations.

    Learning can be two-way in families too. The new generation teaches something real, from new tools to artificial intelligence and data analysis, that adds something new to the business. The older generation teaches negotiation, reading people, and making decisions under pressure, backed by more than 40 years of experience, not just a few books.

    For this relationship to work in practice, it needs a few features:

    • It must be real.
    • It must be regular.
    • The learning side must genuinely ask questions.
    • The results must be put to use.

    When both generations teach each other, neither remains a stranger to the other, and the questions that were always postponed (such as succession and handing over responsibility) begin to feel more like real, comfortable conversations.

    Three Gaps, One Chain

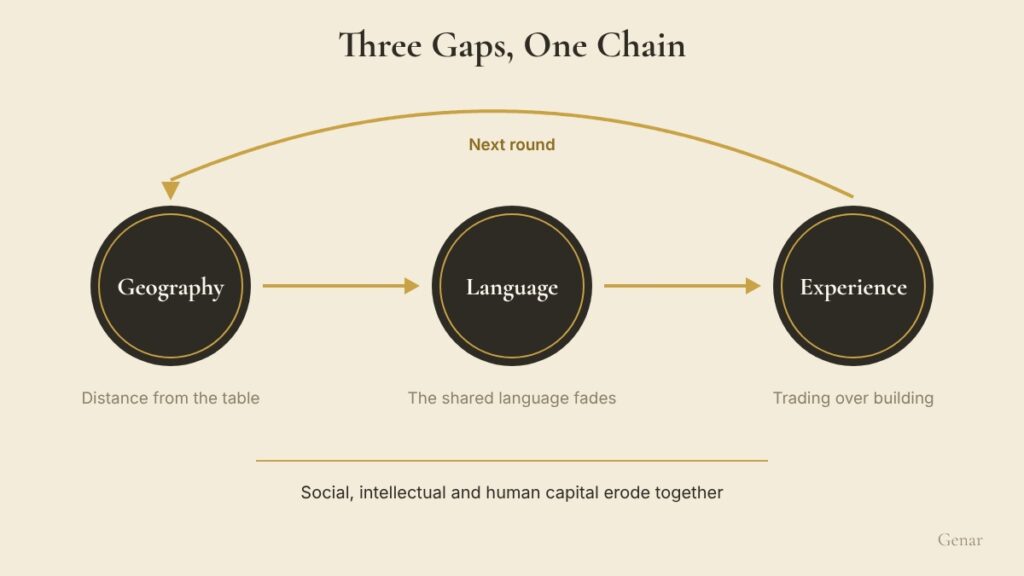
    These three gaps do not work in isolation. Each deepens the others, which is why the erosion of capital is often noticed late.

    Diagram of three circles linked by arrows: geography, language and experience, with a return arrow from the last to the first marking the next round
    The gaps do not work in isolation: distance fades the shared language, a lost language pulls the heir toward transactions, and the next round begins from there.

    Why Do These Three Forms of Erosion Happen Together?

    The chain can start from any link, but it usually unfolds like this: an heir who has moved away gradually understands less of the previous generation’s language. They are no longer at the table and do not see discussions and decisions up close. An heir who does not understand the language takes refuge in what is familiar: numbers and transactions. They see wealth as something to move and cash out, not something to keep. An heir who knows only transactions sees no reason to continue the business, and if profit is all that matters, it can be found anywhere.

    This is where the next round begins: the next generation drifts further away, the previous generation’s language becomes stranger and relationships fade. Social, intellectual, and human capital erode together, even while the financial statements still look good. That apparent health is exactly why no one hears the alarm.

    The Family Compact

    James E. Hughes Jr. says that to preserve its wealth, a family needs a shared compact: a clear agreement on why its members stay together, what the wealth is for, and what responsibility each person has toward it. More importantly, this compact is not inherited. Each generation must accept it anew. A compact made by the previous generation is only a memory until the next generation embraces it.

    Crises are the moments when such a compact is either renewed or abandoned. A family whose members sit together in the hardest years and ask, “Why are we still together?” renews its compact. A family that simply waits for things to improve has abandoned its compact, and nothing seems to happen until the day the heir says there is no place left for them. The next section is a quiz that shows where your family stands on this path right now.

    The Dinner Table Quiz: Where Your Family’s Heirs Stand

    Ask these nine questions at the family table this week. Answer each one for a specific heir, and if you have several heirs, repeat the quiz for each of them separately. Score each question: zero (no), one (partly), or two (yes).

    Social Capital (First Gap)

    1. Has the heir made at least one real decision about the family’s assets or business in the past six months?
    2. Do key people in the family’s network, such as partners and suppliers, know the heir by name?
    3. Does the heir have a reason other than emotion to stay involved with the family’s wealth?

    Intellectual Capital (Second Gap)

    1. Can the heir explain, in their own words, where the family’s wealth came from?
    2. Have they ever made a decision whose outcome took more than a year to unfold?
    3. In recent crises, has what they saw in the elders’ behavior been more building than fleeing?

    Human Capital (Third Gap)

    1. When did the older generation last learn something from them? (Within the past six months: 2; within the past year: 1; longer ago or never: 0)
    2. Has succession actually been discussed, rather than remaining in one person’s mind?
    • If the main decision-maker were unable to make decisions, would anyone know what to do?

    Scoring and Interpretation

    Add up the scores (maximum 18):

    • Below 6: The gaps are making decisions for you. Start preparing your heirs now.
    • 6 to 12: The gaps exist, but they are still in your hands. A little deliberate attention is enough.
    • Above 12: The family is consciously shaping its heir.

    Each section has a maximum of 6 points. The section with the lowest score shows which gap to start with. The total may look good while one form of capital is almost empty.

    One suggestion: have the older generation and the heir each complete the quiz separately, without seeing each other’s answers, and then compare the results. Where the scores differ is usually where the two generations do not understand each other’s language.

    From Stewardship as a Concept to Stewardship as an Experience

    In the final scene of A Separation, Termeh asks her parents to wait outside. The two of them stand apart in the courthouse corridor, behind a closed door, waiting for an answer they themselves spent years helping to shape. Termeh’s answer is the result of everything she saw and experienced in that home.

    Your family’s heir builds their answer from the same things: the city they live in, the crises they have seen and the words they heard, or did not hear, at the table.

    A gap is not closed with advice; it is closed with a shared decision that carries real cost and real responsibility. This is where stewardship turns from a concept into an experience. A steward is someone who sees wealth as something held in trust for the next generation and takes responsibility for preserving it. Such a view cannot be passed on through reading and listening alone. The heir must step into this role, make decisions, and stand by them. Genar’s Process was created to build exactly this experience.

  • Wealth Transfer Isn’t Just About Money

    Wealth Transfer Isn’t Just About Money

    Intergenerational wealth transfer is a sensitive subject for families, particularly wealthy ones. Yet they generally make the same mistake: they start with the money, turning first to investments, taxes, legal structures and wills. A question is asked far less often: before any money is lost, what else has already been lost?

    Ascending staircase chart of seven dark steps with gold edges and dots on a cream-to-gold gradient background
    What built the wealth does not pass to the next generation by itself. That is what is lost before the money.

    Behind every great fortune lie years of decisions, risk, and experience. The problem is that what enabled one generation to build wealth does not automatically pass to the next. A family may have designed intricate legal structures for its assets yet have no plan for preparing the people who will one day steer those assets.

    Perhaps this is exactly where the paths of two families diverge. Some fortunes erode by the second or third generation, while others remain standing even after major upheavals. The real question is not “What will reach the next generation?” It is “Has the next generation been prepared to preserve family wealth and to steer what it receives?” In this Genar article, we address that question.

    When Three Lives Rest on One Asset

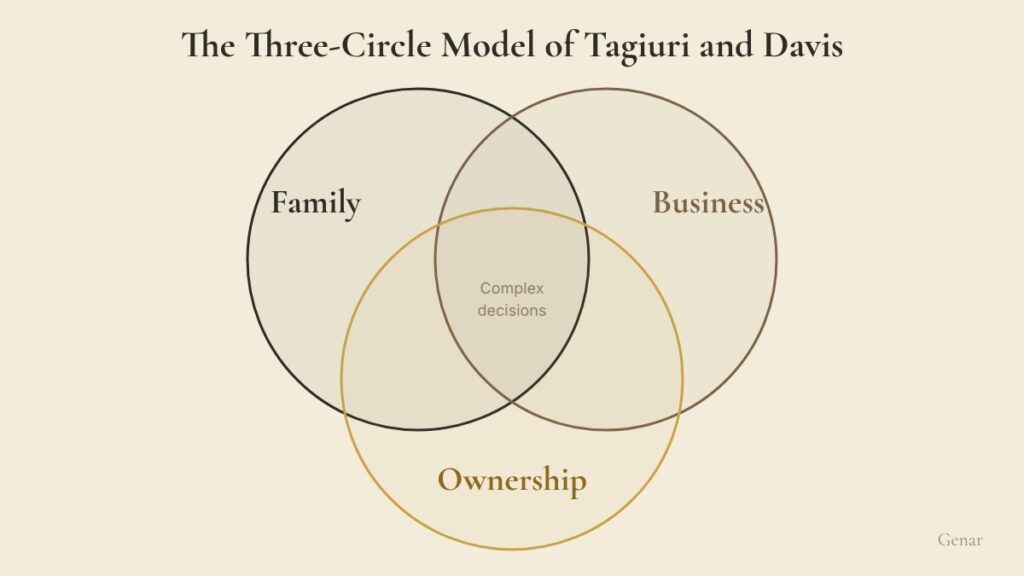
    A family that owns a family business or substantial wealth does not face a simple system. In 1978 at Harvard Business School, Renato Tagiuri and his doctoral student John Davis began developing a framework that would later become one of the best-known models in the field of family business: the Three-Circle Model of the family business.

    The framework separates three domains: family, ownership, and business. The idea first took shape in the work of two researchers in the 1970s, appeared in Davis’s doctoral dissertation in 1982, and eventually became one of the most-cited papers in the field through an article titled “Bivalent Attributes of the Family Firm” in 1996.

    The model’s core idea is simple and practical: not all family disputes are disputes between people; many are disputes between roles. A father who is the principal owner of the company says the final decision is his, while his son, the CEO, believes the authority to manage should rest with him. Both may be entirely reasonable from their perspective. The problem is not their personalities; it is a mistaken understanding of ownership and management, two concepts that must not be confused.

    As the family grows, this complexity grows with it. The number of owners increases, some enter the business, and some stay outside; under these conditions, a simple family relationship must answer emotional, ownership, and management concerns at the same time.

    Venn diagram of three overlapping circles labeled family, business and ownership, with complex decisions at the center where all three meet
    The Three-Circle Model of the family business, presented by Renato Tagiuri and John Davis

    This is exactly where structure becomes important. One person can be a family member, an owner and a manager at the same time. Another can be only a family member and owner with no role in management. A professional CEO can run the company with no family relationship at all. A sentence such as “This decision is in the family’s interest” is therefore not enough on its own. One must ask: in the interest of the family in which role, and in the interest of which generation?

    The Family Needs Governance Too

    When governance comes up, the mind usually goes to the board of directors and the bylaws. But a family that owns a business faces another question: how does the family itself make decisions?

    In the family business literature, this is called family governance. It means creating mechanisms for dialogue, decision-making, role definition and dispute management among the family, ownership and the business. The family council, the family assembly and the family charter are among the tools that more complex families use for this purpose.

    But the philosophy behind these structures matters more than their impressive titles: important issues should not be resolved for the first time in the middle of a crisis. What effect would it have on the business if one family member wanted to sell their shares? What disputes would arise if one person wanted to join the business and the others believed they lacked the necessary qualifications? These are not questions that can be answered with rules written in a moment of crisis. Good governance is not meant to eliminate disagreement; it is meant to keep disagreement from dragging the entire system down.

    But Structure Does Not Build People

    Now suppose the family has taken all these steps: it has set the rules, formed a board, refined the ownership structure and drafted the contracts with precision. All of this is necessary, but one question remains: are the people who will make decisions within this structure prepared for it?

    A structure can specify who has the right to vote, but it cannot give anyone the power of judgment. A contract can determine who owns what, but it cannot teach an heir when to hold an asset and when to change it. This is where the issue of succession shows itself.

    Being an Heir Is a Status; Becoming a Successor Is a Process

    Someone may become the heir to a large business merely by being born into a family. But no one becomes a leader by birth alone; leadership has to be built. The next generation needs the chance to make decisions, accept responsibility, face the results of its own choices, make mistakes and learn from them.

    In the family business literature, successor development is not merely the transfer of a title or shares; it is the simultaneous preparation of the family and the business to continue on their path in the next generation. An heir receives something, but a successor has acquired the ability to continue that path. The two concepts are not the same, and this is where intergenerational wealth transfer goes beyond a purely legal matter.

    Succession planning is usually a gradual path: first learning, then participating in some decisions, accepting real responsibilities, gaining greater authority at the next step and finally, if the person has shown the necessary competence, reaching a position of leadership. Successful succession does not happen on the day of the transfer; it must have been built years before.

    Financial Literacy Is Not Enough

    Suppose the next generation knows what a company is worth, what a balance sheet is and what return an asset yields. Does this knowledge mean readiness to steer wealth? Not necessarily. In the real world, important decisions do not always have a single right answer or a clear formula. What if the market crashes? What if the best economic decision conflicts with the wishes of part of the family?

    This is where financial literacy differs from competence in steering wealth. Financial literacy helps a person understand the numbers; competence helps a person exercise judgment when the answer is not known in advance.

    Wealth Is Not Always Visible in Financial Statements

    One key concept in family business research is socioemotional wealth: the values a family derives from owning and controlling the business that appear in no financial statement, such as family identity, control, belonging and the continued presence of the family.

    Luis Gómez-Mejía and his colleagues examined this concept in a well-known 2007 study of family olive oil mill owners in southern Spain. They showed that, to preserve this kind of wealth, families sometimes make decisions that look purely risky from an economic standpoint. The families chose between joining a cooperative (less business risk but loss of family control) and remaining independent (higher risk but retained control), and a large share preferred independence.

    Suppose a family receives a very large offer to sell its company. Financially, selling may be the best option, yet the family refuses. This decision is not necessarily irrational. Perhaps the company is not merely an asset to them; it is part of their identity, their name is on it and their history was formed within it. Before judging a family’s decision, ask what that family considers valuable. Sometimes the answer is not money.

    When Values Are Not Defined

    The problem begins when a family has never had a real conversation about its values. In such circumstances, in every dispute each person will hold their own definition of the “family’s best interest.” One member believes the company should be preserved because it is the family legacy. Another holds that the father was a risk-taker oriented toward growth and would have changed the company if he were alive today. Both consider themselves loyal to the legacy; only their definitions of legacy differ.

    For this reason, family values should not be merely a pretty sentence on the wall; they must show themselves in real decisions. What must never be sacrificed? If a conflict arises between preserving the legacy and building the future, which takes priority? Such conversations may seem unnecessary on calm days, but they are vital precisely for difficult days.

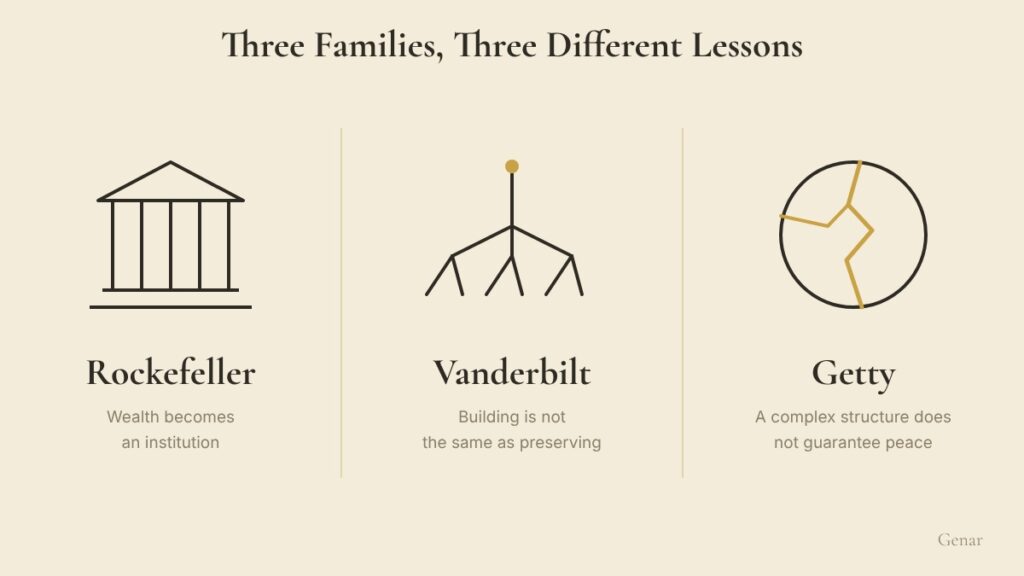
    Three Families, Three Different Lessons

    The history of wealthy families offers no definitive formula for continuing a family business. However, three stories in particular clarify the question of intergenerational wealth transfer: the Rockefellers, the Vanderbilts and the Gettys. All three built immense fortunes, yet each carries a different lesson about how that fortune endures.

    Three line icons side by side: a columned building for Rockefeller, a branching tree for Vanderbilt and a cracked circle for Getty
    Rockefeller turned wealth into an institution. Vanderbilt showed that building and preserving are different skills. Getty showed that a complex structure does not by itself prevent disputes.

    Rockefeller: When Wealth Becomes an Institution

    John D. Rockefeller, founder of Standard Oil, built one of the largest fortunes in American history. But his story is not only about how much money remained for later generations. In 1913, the Rockefeller Foundation was established with a mission the foundation says has not changed since its first day: to promote the well-being of humanity throughout the world.

    Between 1913 and 1929, the Rockefeller family devoted substantial capital to the foundation, which, by its own figures, has distributed more than $26 billion in philanthropic capital worldwide over more than a century.

    The interesting point is that Rockefeller did not think only about “holding on to money.” Part of his wealth entered an institutional structure meant to serve a specific purpose, independent of any one person’s lifespan. The lesson of this story is not to establish a charitable foundation. The deeper lesson is that wealth can shift from a personal asset to an institution with a purpose and a time horizon independent of any one individual. The larger question than “Who owns it?” is “What is meant to remain after the owner?”

    Vanderbilt: When Building and Preserving Are Two Different Skills

    Cornelius Vanderbilt started in shipping, then moved into railroads and ultimately, by building the New York Central railroad empire, created one of the largest personal fortunes of nineteenth-century America. At his death in 1877, his estate was estimated at about $100 million, a figure that at the time exceeded the U.S. Treasury’s holdings. His son William Henry, who inherited roughly 95 percent of this fortune, not only preserved it but doubled it in less than a decade.

    The Vanderbilt story is not one of failure immediately after the founder. It is a story of serious crisis in later generations. After William Henry died, the fortune was split among his children; part of the next generation lost interest in the railroad business, and estate costs and a lavish lifestyle rose. According to historical accounts, when about 120 Vanderbilt descendants gathered in 1973 at the university Cornelius himself had founded, not one of them was a millionaire.

    Behind this lay a combination of dispersed ownership, changing economic conditions, an expensive lifestyle and the growing distance of later generations from the process that had created the wealth. The skill of building wealth is not the same as the skill of preserving it. Cornelius had to make decisions under competition and uncertainty; later generations encountered only the outcome of a path, not the difficulty of building it.

    Getty: When Great Wealth Builds a More Complex System

    1. Paul Getty built his immense fortune mainly in the oil industry. But the story of the Getty family is less about “preserving or losing money” than about the growing complexity of ownership, trust structures and family relationships between generations. The Getty family trust, formed in 1934 with about $3.3 million, became, after he died in 1976, the center of one of the most contentious family disputes in wealth history.

    According to Fortune magazine’s reporting from that era, Getty’s children and grandchildren entered a long legal battle over control of roughly $4 billion in assets and the way the trust was run. The battle even involved the rights of descendants not yet born, and it finally ended in 1985 when the trust was divided into several smaller parts among the different branches of the family.

    As the number of stakeholders grows, the question shifts from “How much money do we have?” to “Who decides, who has control and, if the family disagrees over the interpretation of ownership, who arbitrates?” The Getty story shows that a complex legal structure is not, on its own, a guarantee against disputes. Without governance, dialogue and clear rules, the structure itself can become part of the problem.

    From Three Stories to One Pattern

    The Rockefeller, Vanderbilt and Getty stories are not identical, but together they make one point clear: in each generation, wealth faces a different problem.

    The first generation is usually occupied with creating value: how does one build something that does not yet exist? The next generation must learn to steer well something it did not build itself. In later generations the question grows more complex: how does one build a shared path amid multiple owners and differing interests? For this reason, intergenerational transfer is not an “event”; each generation must prepare for its own particular problem.

    Four Layers That Must Be Built Together

    To turn this discussion into a practical framework for preparing the next generation to manage wealth, we can see it in four layers.

    1. Understanding

    The next generation must know how this wealth was built, what decisions drove it, what risks were taken and what mistakes were made. This is the difference between knowing an asset’s value and understanding its story.

    2. Competence

    Knowing is not enough; the next generation must have the chance to make decisions. The path is usually gradual: learning, participation, responsibility, authority, leadership. The goal is not for the next generation to copy the founder. The goal is for them to create value in their own time, under their own conditions.

    3. Governance

    When a family grows, the family relationship is no longer enough to resolve every issue. It must be clear who owns, who manages, who makes the final decision and how disputes are resolved.

    4. Meaning

    Ultimately, the family must know why it wants to continue this wealth. Is the goal only to preserve the value of the assets? Is creating opportunity for the next generation more important than ownership? Does “legacy” mean preserving exactly what the founder built? Or does it mean preserving the ability to create something valuable in every generation?

    These questions have no single answer, but a family that has not talked about them will likely be forced, in the hardest moment, to find answers on the spot.

    Owner or Steward?

    Another useful concept in this discussion is stewardship. Stewardship theory was proposed by James Davis, David Schoorman and Lex Donaldson in 1997 as a counterpoint to the prevailing view of the manager as a purely self-interested individual. They showed that under the right conditions, people can see themselves as serving the long-term interests of the organization and the collective, not only their personal interests.

    For wealthy families, this concept raises an intriguing question: are they the owners of these assets or their stewards for the future? These two views produce different decisions. If ownership is only an individual’s “right,” decisions are based on personal interest. But if ownership is joined by stewardship, another question enters: what does this decision mean for those who come later? Stewardship adds a time horizon to the decision without depriving the owner of the freedom to choose.

    A Simple Test for Families

    Suppose you own a business or a substantial part of the family wealth. Ask yourself these five questions:

    Does the next generation know how the family wealth was built?

    Has it ever had the chance to make real decisions and experience their results?

    Can it distinguish among the roles of “family member,” “owner” and “manager”?

    Has our family discussed possible future disputes before they occur?

    If the next generation has to change part of what we have built, does it know what must be preserved and what can be changed?

    If the answer to some of these questions is “no,” it does not necessarily mean failure. But it is an important sign that part of the transfer architecture has not yet been built.

    What Intergenerational Wealth Transfer Must Carry

    The question of wealth transfer cannot be solved with a document or a legal structure alone. These tools are necessary, but they are only part of the solution. Alongside assets, other things must also be transferred: knowledge for understanding, competence for making decisions, governance for managing complexity, and meaning for knowing why this path should continue.

    At first glance, the question is what intergenerational wealth transfer should transfer. At second glance, the question is what system must be built so that the next generation can make sound decisions with what it receives. These two questions are not alike, and this very difference separates one family’s path from another’s. In Genar’s articles on family and wealth, we have explored this subject from other angles as well.

    From Wealth Transfer to an Architecture of Continuity

    A family may use the best lawyers, financial advisors, and investment managers, benefit from a precise ownership structure, and have all contracts properly concluded. But if the generation that will make the decisions has not been prepared for that responsibility, part of the problem remains unresolved. On the other hand, educating one generation is not enough on its own either. If roles are unclear and family members have not discussed shared values and the future, even capable people may fail to be productive within a dysfunctional system and may fail to chart a sound path forward.

    Continuity of a family business is therefore not the product of a single element; people, structure and meaning must be designed together. This is where wealth transfer shifts from a legal event to an intergenerational project. The question for a family thinking about the future is not only “What are we leaving to our children?” The harder question is this: if everything is placed in their hands tomorrow, will they be prepared for the decisions they must make after us?

    A contract can transfer ownership, a structure can regulate power, capital can create opportunity, but competence must be built, governance must be designed and legacy must be given meaning.

    Perhaps the most lasting thing one generation can leave the next is not the wealth itself but the ability to build a future in which that wealth can continue to create value. This is the point where Genar’s approach to preparing the next generation begins.

  • Wealth Is Built by the Mind, Not Just Money

    Wealth Is Built by the Mind, Not Just Money


    A financial mindset is how the mind gives meaning to money: the framework that shapes how a person feels about money and, on that basis, what they decide. The absence of this mindset is the most precise answer to one of the biggest questions many wealthy families face: why does wealth that the first generation built through hard work, scarcity, risk-taking and difficult decisions fail to grow in the same way in the generations that follow? The financial mindset answers that the loss or stagnation of wealth usually stems from neither a lack of resources nor a lack of opportunity. The problem lies deeper than tools and means: in the mind that has to make decisions about money.

    In this Genar article, we first examine where a financial mindset comes from and how it differs from financial literacy. We then unpack the behavioral mechanisms behind poor financial decisions, such as mental accounting and rationalization. Finally, we outline a practical path to building a strong financial mind.

    Wealth Erosion in Later Generations

    The first generation grew up in conditions where every financial decision was part of life, from managing scarcity to facing the consequences of their choices. That experience gives the mind a structure that can tolerate volatility, analyze consequences and understand risk.

    Later generations, however, often grow up with a different experience. For them, money has been “the status quo,” not the result of a difficult journey. Naturally, such a mind has never experienced parts of the cognitive architecture needed to manage wealth, even if it has the necessary skills and tools at its disposal.

    Why Tools Alone Are Not Enough

    The classic tools of wealth management (financial planning, legal structures, investment techniques) rest on one important assumption: that the person using them has a structured, mature mind. That means a mind that can interpret data, manage emotion and see long-term consequences.

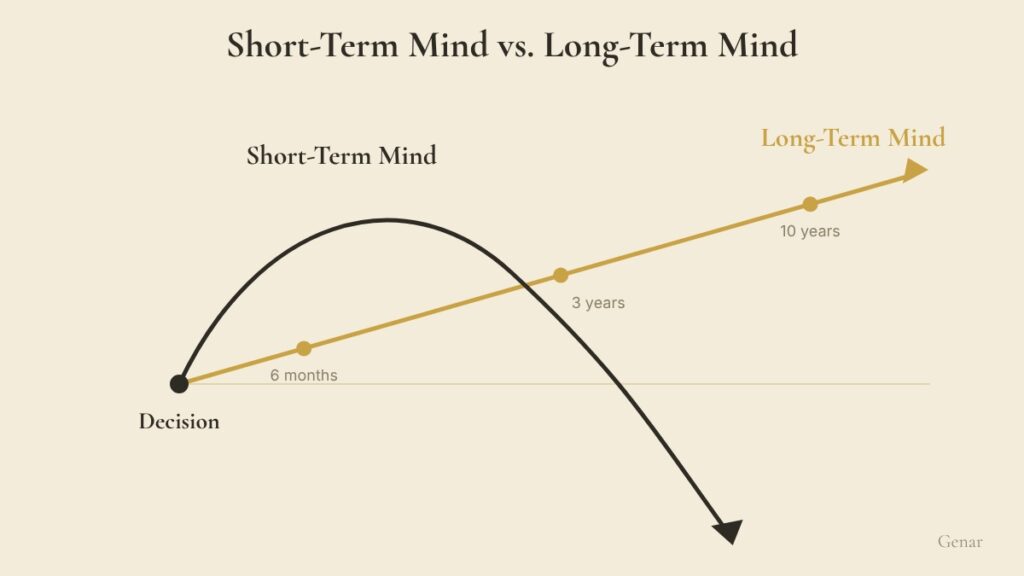
    Until that mental infrastructure is in place, the tools lose their effectiveness. Many financial mistakes stem not from a lack of tools but from a lack of mental architecture. Such a mind misjudges risk, does not learn from feedback, sees decisions in the short term and draws no line between emotion and numbers. So the real question is not “How do we transfer more money?” It is “Along with the money, are we also transferring the ability to think with money?”

    What Is a Financial Mindset?

    A financial mindset should not be reduced to a set of information or skills that a few classes or a handful of simple tips could explain. It is the way the mind gives meaning to the concept of money. It is a framework that determines how the mind sees money, how it feels about it and how it organizes small and large decisions within its own inner narratives.

    When we talk about this concept, we do not mean a new body of “knowledge.” We mean a cognitive architecture that sits beneath the surface of everyday decisions. It shapes how a person behaves around money, even if they are unaware of the mechanism. The mind first builds a narrative, then activates an emotion and decides on that basis.

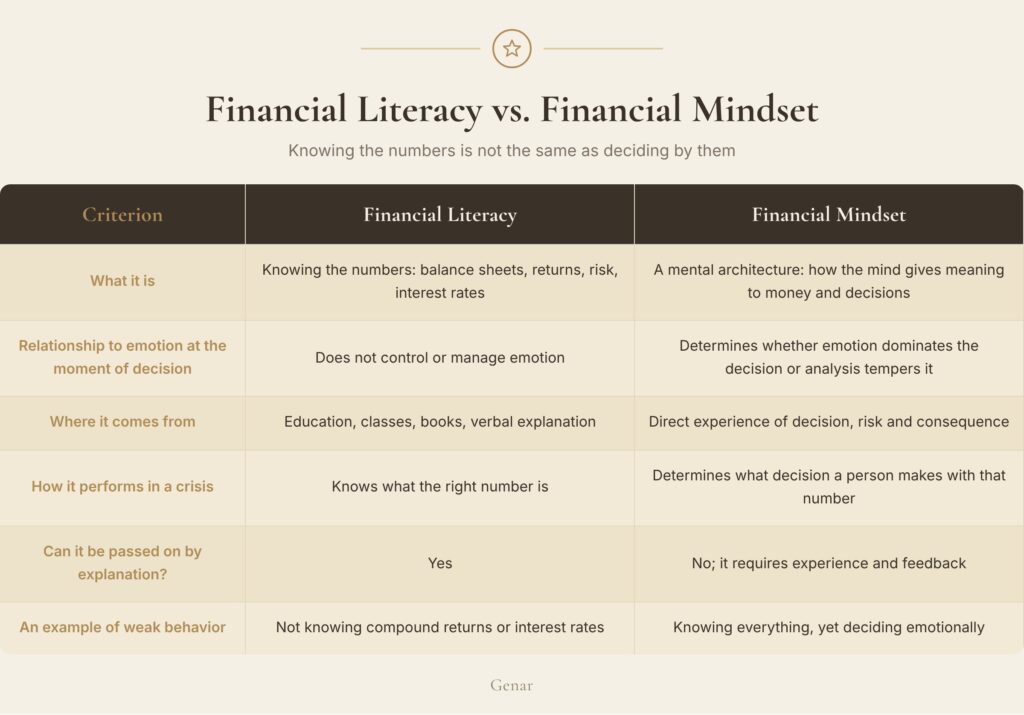
    Financial Literacy vs. Financial Mindset

    Although both concepts relate to money, people often confuse them. One is about “knowing”; the other is about “behaving.” You can be highly financially literate (read a balance sheet, understand compound returns and calculate interest rates) and still act entirely on emotion under the pressure of a real decision. The table below illustrates the difference:

    Table comparing financial literacy and financial mindset across six criteria, from what each is to how it performs in a crisis
    Financial literacy shows what to know. Financial mindset decides what a person does with it under pressure.

    We can therefore conclude that financial literacy is necessary, but not sufficient.

    How Does a Financial Mindset Work in Everyday Life?

    Many people assume a financial mindset shows up only in the big moments of financial life, such as buying an asset, choosing a career or deciding to invest. But this mindset reveals itself less in major decisions than in small, seemingly insignificant daily choices.

    For example, some people are comfortable spending a small amount but hesitate when faced with an important, necessary expense. Others overreact to a price increase. Some, when they see an investment opportunity, are driven by fear of missing out rather than analysis. In short, in practice, a financial mindset shapes:

    what a person considers “valuable”

    which expenses are “necessary” or “unnecessary”

    which decisions are seen as an “opportunity” and which as a “threat”

    when spending brings guilt and when it brings satisfaction

    All of these are outputs of a mental architecture formed over years in each person’s subconscious.

    Why Is Wealth Built but Not Sustained?

    This difference in experience made the first generation’s mental architecture “constructive,” “analytical,” and “long-term oriented.” For the next generation, however, money was part of the environment rather than the product of a decision. A father who does not want his child to suffer unintentionally removes the pain of decision-making from the child’s life. This creates a different starting point: a generation enters a game whose rules it does not know. If we remove every hardship from the next generation’s path, we may also take away their chance to develop essential capabilities. Genar’s approach is designed to address exactly this challenge.

    In such a context, it is natural for risk to become a source of anxiety rather than something to manage. Spending becomes an emotional reaction rather than an instrument of responsibility. And money, instead of being a source of responsibility, becomes merely a means of further consumption.

    This experience gap is a key driver of wealth erosion in later generations. It is also where the greatest paradox of successful families takes shape: preserving wealth without restricting the next generation’s ability to use it. This is where the concept of stewardship in family wealth becomes important. The next generation is not merely the owner of the wealth but its steward, charged with preserving it and passing it on to the generation after. For a fuller look at this topic from the perspective of family structure and governance, see our article Wealth Transfer Is Not Just About Money.

    Why Can’t a Mind Without Financial Experience Make Sound Decisions?

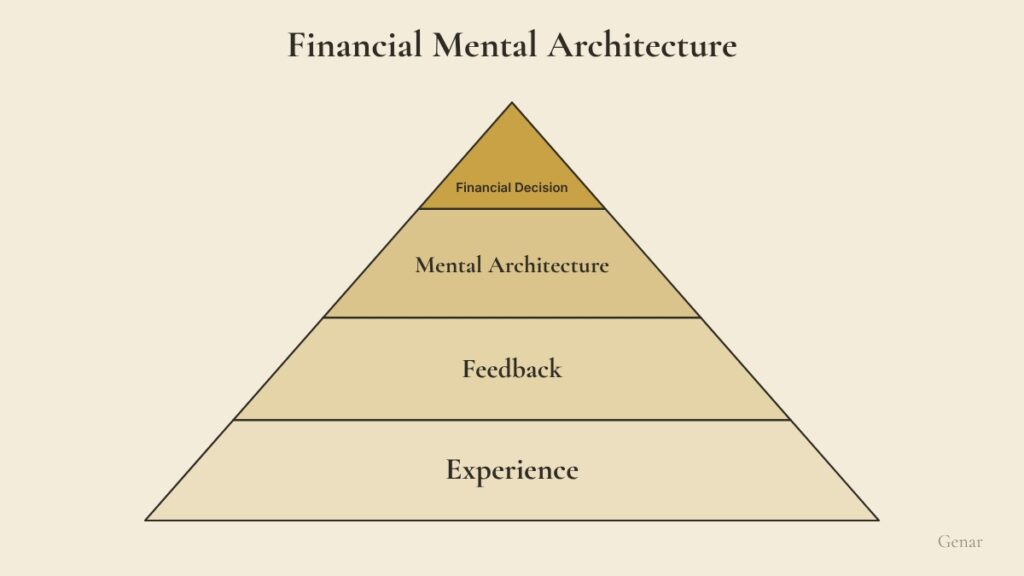
    To build stable decision-making patterns, the human mind needs three elements: experience, consequence and feedback. When these are missing, the mind turns to shortcuts such as guesswork and justification to interpret financial reality. Without real experience, a person repeats the same mistakes and acts on emotion instead of analysis. After a financial failure, such a mind justifies the decision instead of examining its consequences.

    In these situations, many wealth creators say, “But I explained everything.” Explanation, however, cannot replace experience. Until the mind engages with the real experience of decision, risk and consequence, it cannot build a financial mental architecture.

    A child who has never been allowed to make a wrong decision has never actually practiced decision-making. They have only learned “what not to do,” not “what happens if I do it.” A mind without real feedback does not correct its mistakes. It justifies them and repeats them in different forms.

    A financial mindset, then, is not a surface skill. It is a cognitive infrastructure that shapes financial behavior at its deepest level. It determines how we spend, how we take risks, how we make mistakes, how we learn from experience and how we hold up under financial pressure. Without this mental architecture, no financial tool, however advanced or simple, can guarantee sound decision-making.

    When Emotion Outpaces Analysis

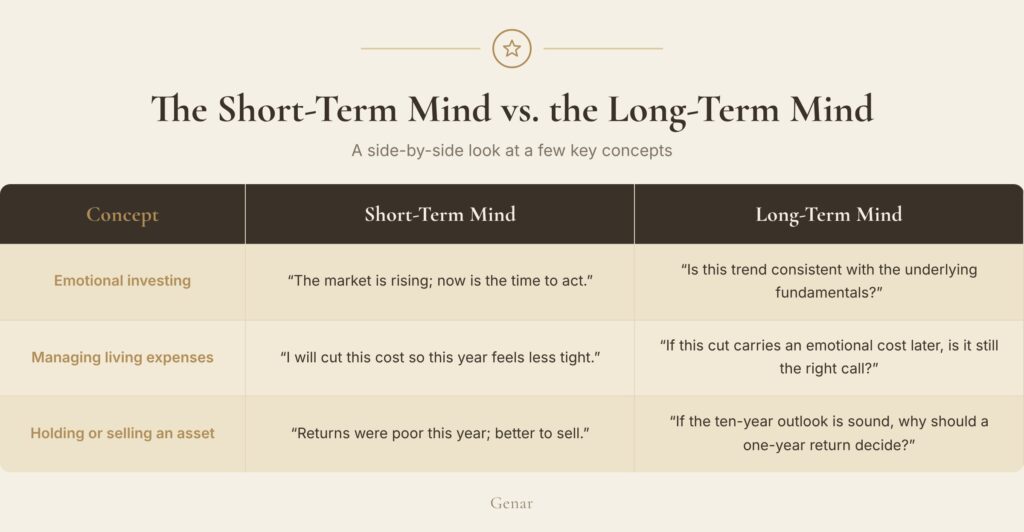
    Let us go deeper into the mind. To the human mind, money is not simply a “number.” It directly triggers emotion. Our minds generate feelings before they calculate. Fear, excitement, guilt, pleasure and the fear of missing out activate far faster than analysis, and in many decisions they quietly take the wheel.

    Financial markets show this mechanism clearly. When prices rise, the fear of missing out puts pressure on a person, even if there is no analysis behind the move. When prices fall, the same mind that was full of optimism a few days earlier now acts in panic. The data has not changed; the mind’s reference point has.

    The same behavior appears in everyday life. A person may feel guilty buying a small item yet feel motivated to buy a luxury one, because the mind places the two in “different emotional accounts.”

    Analysis is always slower than emotion. Without strong mental architecture, a person usually makes financial decisions based on immediate reaction, fear of loss, the need for quick gratification or the urge to prove themselves, rather than long-term thinking. The result is a set of familiar behaviors:

    buying an asset simply because its price is rising

    holding on to a losing investment to “make it back”

    spending windfall money without thought or planning

    resisting necessary expenses

    making showy decisions to maintain an outward image

    This brings us to the important subject of mental accounting.

    Why Financial Mistakes Repeat

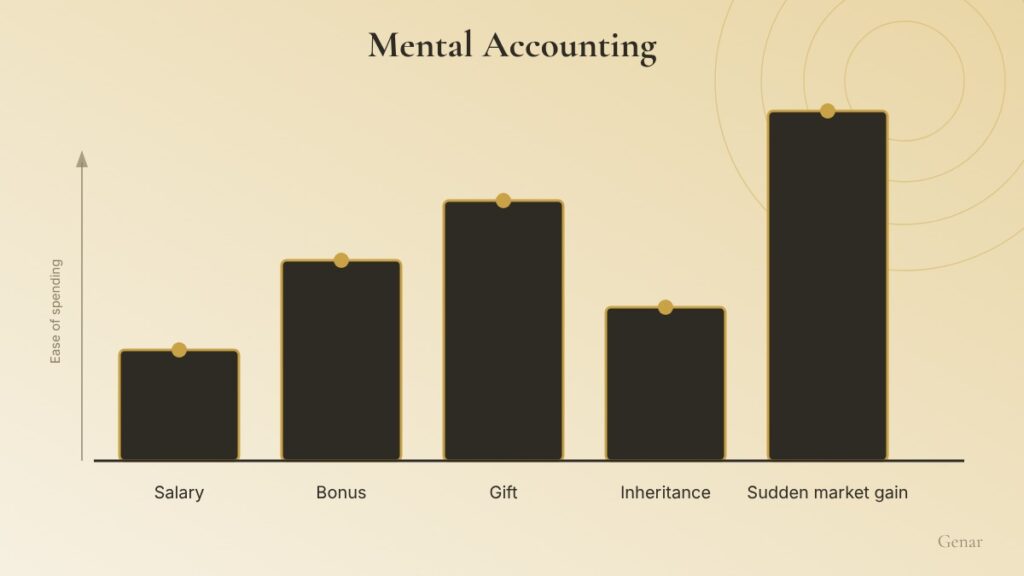
    When facing financial decisions, the human mind does not see money as a single numerical unit. It relies on two mechanisms to make these decisions. The first is what Nobel Prize–winning behavioral economist Richard Thaler calls “mental accounting” (“Mental Accounting and Consumer Choice,” Marketing Science, 1985). Under this mechanism, the mind files every incoming sum in a separate account: salary, bonus, gift, inheritance, savings, capital and so on. It then makes divisions like these:

    gift money is different from salary money

    a bonus counts as a “right to enjoy”

    leisure spending comes out of the “emotion account,” not the “expense account”

    Mental accounting makes financial behavior seem more manageable, but it can keep a person from making the decision the data says is right. Suppose a child is given pocket money, education money, leisure money and investment money without any meaning or rules attached. The child’s mind will not see these as the same money, and that inconsistency comes from these separate accounts.

    Thaler showed that the human mind works like hidden accounting software (“Mental Accounting Matters,” Journal of Behavioral Decision Making, 1999). Unlike real financial software, however, this system is not always rational. Sometimes it helps us feel in control, but more often it leads to decisions that do not match financial reality. So a significant part of financial behavior depends not on the “amount” of money but on the meaning the mind attaches to it.

    Money Is Not a “Number”; It Is an Identity

    Our minds give every kind of money an emotional identity, and decisions that seem irrational are the output of this identity-making. A young person may resist spending their salary yet spend gift money without a moment’s hesitation. They may be strict about paying their mortgage yet feel completely free when it comes to leisure, even when these decisions make no economic sense. These differences reveal not financial behavior as such, but the psychological structure of money in the mind.

    Windfall Money Is Easy to Spend—But Why?

    Money that arrives easily and unexpectedly (such as an inheritance, a gift or a sudden market gain) is stored in a mental account that is not subject to much financial discipline. Richard Thaler and Eric Johnson called this the “house-money effect” (“Gambling with the House Money and Trying to Break Even,” Management Science, 1990). The mind does not see such money as the product of effort. So it is easier to spend, the person feels less guilty spending it, and they usually make no particular long-term plan for it. As a result, instead of being a tool for building the future, this money often becomes a tool for short-term pleasure.

    Not Touching Savings, Even When It Makes Sense

    One of the strangest financial behaviors is that many people refuse to draw on their savings or principal, even when it is necessary. This behavior is not necessarily wrong, but it shows that our minds have built internal rules that sometimes lead us away from the right decision. Hersh Shefrin and Richard Thaler showed that people treat money in different accounts as differently “spendable”: current income is spent easily, while savings and accumulated assets are treated as almost untouchable (“The Behavioral Life-Cycle Hypothesis,” Economic Inquiry, 1988). In practice, this shows up as internal rules such as “Savings are sacred,” “Never touch the principal” and “This money is for future goals.” These rules appear protective, but they can push a person toward irrational decisions. This is exactly the point at which someone would rather take out a high-interest loan than draw on their own savings.

    Bar chart of how easily five kinds of money are spent: salary lowest, sudden market gain highest, and a gift easier to spend than an inheritance
    Money that arrives easily is spent easily. The mind opens a separate account for every source.

    The mind treats each kind of money differently: the more of a “windfall” the source, the less mental resistance there is to spending it

    Common Mistakes Caused by Mental Accounts

    A financial mindset makes a person more aware of their mental accounts and the mistakes these categories create. Some of these mistakes cost potential investment opportunities or the chance to earn more:

    The sunk cost effect: Because money has already been paid for something, the mind sees it as an “unclosed account” and refuses to let it go, even when walking away is the best decision.

    Artificial separation of money: A person may resist a small expense yet be indifferent to a large one on the same day, because the mind has placed each in a different account.

    These patterns show that much of financial behavior results not from analysis but from hidden structures in the mind.

    Rationalization

    The second mechanism is justification, or rationalization. Ran Kivetz and Itamar Simonson studied how people deal with the guilt of choosing pleasure over necessity (“Self-Control for the Righteous: Toward a Theory of Precommitment to Indulgence,” Journal of Consumer Research, 2002). Their research shows that indulgent choices create psychological discomfort, and people look for reasons that make the choice feel deserved. One of the strongest reasons is effort: the sense of having “earned” the right to indulge.

    That is why so many people justify unnecessary spending with lines like “I earned this,” “This comes out of my fun budget” or “You only live once.” In these moments, the mind makes a wrong decision feel “right.” This is exactly why financial mistakes repeat: the mind does not question its decision; it justifies it.

    Behavioral Patterns of the Younger Generation

    Younger generations, especially those raised in affluent families, have usually not experienced the financial pressures of previous generations. This difference in experience makes certain behavioral patterns more pronounced. These patterns seem natural but can, in practice, derail a financial path. The most common financial mistakes of the younger generation generally share three roots:

    Justifying wrong decisions: The same justification mechanism shows up here. When the cost of a mistake has never been felt directly, it is easy for the mind to “make up a story” for a bad decision, such as “That money didn’t really matter” or “I needed to spend to feel better.”

    Misjudging the value of money: When money has always been “available,” the mind naturally gives it less psychological weight. As a result, the ability to tell a necessary expense from an emotional one weakens.

    Not grasping the long-term consequences of small decisions: Without direct experience of risk and consequence, the younger mind sees decisions as “momentary” and pays little attention to a small expense today. Yet the same behavior, repeated over time, shapes one’s financial future.

    These three factors do not simply lead the younger generation to make “bad” decisions. They leave young people’s minds unprepared for complex financial decisions. Until experience, feedback and analysis enter the picture, these patterns continue.

    Four-tier pyramid, from base to apex: experience, feedback, mental architecture and, at the top, the financial decision
    A financial mind is built from experience and feedback. The decision is only the last layer.

    A financial decision is the tip of a pyramid built on experience. Without real experience and feedback, a financial mental architecture cannot form

    How the Minds of the Wealthy Work Differently

    When dealing with money, many people focus only on figures and prices, and others rely solely on emotion. But those who manage wealth consistently well have a mindset with a range of mental models and an analytical approach grounded in financial reality.

    One of the most fundamental differences between a professional financial mind and an ordinary one is a stable time horizon. People whose financial decisions produce lasting results over a lifetime analyze their choices within longer time frames. They do not judge them by short-term outcomes.

    Our minds are designed for survival, not wealth management. That is why quick reactions and instant rewards carry more weight in the human nervous system. A small gain today feels more satisfying than a large gain next year. An immediate cost seems scarier than a hidden cost three years out. A decision that pays off “now” looks more reliable, even if it is wrong in the long run. This natural bias is one of the main reasons wealth erodes in generations without financial experience.

    How Does a Strong Financial Mind Escape the Short-Term Trap?

    People with a strong financial mind have grasped one key difference: the short term is easy but dangerous, and the long term is hard but profitable. That is why they ask three simple questions for every financial decision. These questions put a serious barrier in front of emotional decisions:

    If I look at this decision over a six-month horizon, what happens?

    If I look at it over three years, what changes?

    And if I look at it over ten years, is it still a good decision?

    Line chart from the moment of decision: the short-term mind peaks fast then falls, while the long-term mind climbs gently across six months, three years and ten years
    The short-term mind reacts to what is near. The long-term mind judges a decision across ten years.

    The short-term mind peaks quickly and crashes. The long-term mind rises on a gentler slope and builds a more sustainable path to growing wealth


    People who have built or preserved wealth usually share several traits. They do not react emotionally to short-term swings. They prefer following cycles and structures to following the news. They judge assets by long-term quality. And rather than a one-off gain, they seek growth that lasts. To better understand the difference between the short-term and long-term mind, it helps to compare a few concepts side by side:

    Table placing short-term and long-term thinking side by side in three situations: emotional investing, managing living expenses, and holding or selling an asset
    A few key concepts, seen through two kinds of mind.

    Building a Strong Financial Mind: A Practical Path

    You cannot acquire a strong financial mind by reading a few books or watching a few YouTube videos. It is like a muscle that grows through experience, feedback and continuous correction. Behavioral research on financial decision-making agrees on one point: a financial mind comes from “process,” not “knowledge.”

    Michael Mauboussin, financial strategist and author of Think Twice and The Success Equation, has stressed this point for years. In any probabilistic field, including investing, you should focus on the quality of the decision process, not just its short-term outcome, because even a good decision can produce a bad result in the short term. His suggested tool is simple: a “decision journal.” Before each important decision, you record the reasoning behind it, not just the outcome. Below, we look at four practical pillars for building this process.

    1. Real Feedback on Decisions, With Analysis of the Reasoning

    No one has built a powerful financial mind without making mistakes. What sets successful people apart is that they analyze their mistakes instead of running from them. To get better feedback, you can start with the following:

    Record your decisions: Most people do not know why a financial decision was right or wrong because they never wrote it down. Recording makes patterns, mistakes and biases visible.

    Analyze the reasoning, not just the result: A strong financial mind does not only measure the outcome. It assesses the quality of the decision to see whether a gain came from skill or luck.

    Correct quickly, before the mistake repeats: Feedback is only valuable when it immediately changes behavior.

    2. Building Small, Lasting Money Habits

    Durable financial behavior is not built on “willpower” alone. It results from small, repeated habits. Thaler argues that habits should be structured around design more than emotion, an idea he and Cass Sunstein developed in Nudge (2008). Building such a structure requires the following:

    Set a specific time for financial decisions: Decisions made in the moment are shaped by emotion. A decision reviewed at a set time, away from excitement, will be more rational.

    Create personal rules: Examples include “Never make an important financial decision in less than 24 hours” or “Never invest without reviewing the worst-case scenario.”

    Build a monthly review habit: Reviewing your financial behavior each month makes your spending patterns visible. It moves the mind from a sense of being “out of control” to “clarity.”

    3. Strengthening Analytical Thinking and Seeing Opportunity Cost

    This is one of the most important parts of a strong financial mental structure. You can develop it by keeping the following in mind:

    See probabilities, not certainties: A professional mind sees nothing as “certain.” To it, everything is a probability.

    See opportunity cost: Every financial decision means giving up another option. A strong mind also accounts for the decision not taken.

    Use base rates: Before deciding, a professional mind asks, “Over the past ten years, what has typically happened with this type of decision?”

    4. Designing a Personal Financial Decision-Making System

    A strong financial mindset requires a system: a set of rules, habits, schedules and tools that make decision-making predictable and consistent. This system has three components:

    A decision-making structure: A defined process for important decisions: gathering data, reviewing the worst-case scenario, comparing against long-term goals, assessing risk and executing the decision.

    Behavioral boundaries: Limits such as risk tolerance, stop-loss levels, time horizon and permitted asset types protect the mind from emotional reactions.

    Monitoring and control tools: Keeping and using a decision journal, an expense list, a monthly report and a chart tracking progress toward financial goals.

    A Short Exercise for Your Financial Mind

    To keep this discussion from remaining just an idea, write down three important financial decisions you made in the past year. Answer these questions for each one:

    How much time did you spend making this decision? Did you decide on the spot, or did you take months or even years?

    Did you record the reasoning behind the decision anywhere, or do you only remember the outcome?

    If it turned out well, was that the product of analysis or luck? If it turned out badly, was the decision itself wrong, or did circumstances go against expectations?

    In your mind, was this money “earned through work and effort” or “windfall money”? Did that affect how strict you were?

    If you made the same decision today, with some distance from that moment, what would you change?

    If you did not have clear answers to most of these questions, it does not necessarily mean you made bad decisions. It does show that part of your financial mental architecture is not yet written down or conscious. That is exactly where a strong financial mind begins to be built.

    Why the Next Generation’s Financial Future Begins in the Mind

    The mind is a person’s most important financial asset. Neither starting capital, nor tools, nor even technical knowledge can make up for a weak financial mindset. A powerful financial mind, even without substantial resources, can build a path to wealth, correct it and keep it sustainable. What we see across generations is this distinction. The generation that created the wealth built its mind before its tools. The generation that inherits it will lose it just as quickly without this mindset.

    Such a mind can distinguish real patterns from false ones, see multi-step consequences and learn from feedback rather than simply chasing results. That is why people with limited resources but the right financial mindset perform more consistently over the long term than those with more capital but a weaker mindset.

    Wealth passed between generations is not limited to financial assets. An important part is the family’s socioemotional wealth: the relationships, trust and shared values that underpin sound financial decisions.

    Put simply, transferring wealth without transferring mindset is like handing a powerful car to someone who does not yet know where the brake pedal is. A generation’s financial future takes shape in its mental accounts before it is built in its bank accounts. But this mindset does not form on its own. It comes from the real experience of making decisions, making mistakes and accepting the consequences, which is exactly what Genar is designed to build.

    Frequently Asked Questions

    1. How is a financial mindset different from financial literacy?

    Financial literacy means understanding the numbers (balance sheets, returns, risk). A financial mindset is a mental architecture that determines what decisions a person makes with those same numbers.

    1. What exactly is mental accounting?

    Mental accounting is a concept from Richard Thaler. It shows that the human mind sorts money into separate accounts by source, purpose or timing and treats each one differently.

    1. How does the house-money effect influence family decisions?

    When money comes through inheritance or gifts rather than direct effort, the mind values it less than money earned through work and spends it more easily. This is one of the most common reasons inherited wealth erodes quickly in the next generation.

    1. Why is simply “explaining” money to children not enough?

    The human mind builds decision-making patterns from direct experience of risk, mistakes and consequences, not from listening. Explanation builds knowledge; experience creates mental architecture.

    1. What decisions does the sunk cost effect influence?

    When money has already been spent on something, the mind tends to keep going to “justify” the past cost, even when continuing no longer makes sense. This effect shows up again and again in people holding on to losing investments, failing businesses and even working relationships.